Solar panel insurance, Viriyah Solar Shield, from THB 933 per year
- Updated: 30 October 2026
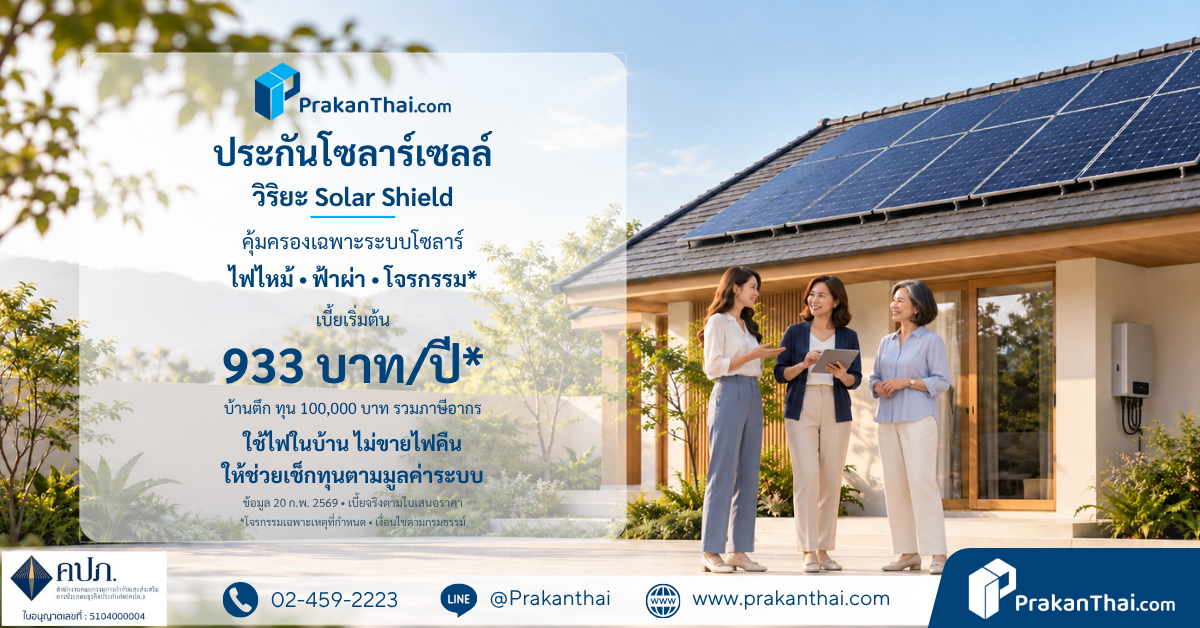
Solar panel insurance, Viriyah Solar Shield, from THB 933 per year
Premium data as at 20 February 2026 · compiled by Prakanthai.com
Underwritten by Viriyah Insurance Public Company Limited
Premiums from THB 933.04 per year (sum insured THB 100,000), with sums insured up to THB 5,000,000 to choose from, including tax and duty
Highlight: insures only the rooftop solar system on the house, with the sum insured set by you to match the system's value
You have put solar panels on the roof for several hundred thousand baht. When the rainy season brings storms and lightning near your home, you start to wonder who pays if the panels or equipment are damaged.
Does your home insurance already include the solar system, and if you take out separate cover, how much will it cost?
Who is Viriyah Solar Shield solar panel insurance for, and how much is the premium?
The short answer: Viriyah's Solar Shield 2026 solar panel plan suits owners of residential homes who have rooftop solar for their own use and do not sell power back. It covers the panels, attached equipment and the control box against fire, lightning and explosion, for the actual loss up to the sum insured, plus theft and third-party liability of THB 500,000. Premiums start at THB 933.04 per year (sum insured THB 100,000, masonry house, data as at 20 Feb 2026). The actual premium depends on the sum insured, type of house and period of insurance.
What does Solar Shield solar panel insurance cover?
Insured property: solar panels installed on the roof of the house, including attached equipment and the control box, owned by the insured. The limits in the table apply per occurrence and per year.
| Coverage | Limit | Conditions |
|---|---|---|
| Fire, lightning, explosion, impact by vehicles or animals, aircraft, water damage | Actual loss, up to the sum insured | Water damage excludes flood |
| Smoke damage | Actual loss, up to the sum insured | – |
| Natural perils group (standard): windstorm, flood, earthquake, hail | Combined limit of up to THB 20,000 | – |
| Windstorm / flood / earthquake / hail (extended cover) | THB 20,000 per peril | – |
| Damage to electrical equipment (Electrical Injury) | THB 20,000 | – |
| Riot and strike | THB 10,000 | – |
| Fire-fighting costs / debris removal and clearance costs / surveyor and repair-supervision fees | 5% of the sum insured each, up to THB 100,000 | Only where caused by a peril in the fire insurance group |
| Theft with signs of forced entry, snatch robbery, armed robbery | Actual loss, up to the sum insured | First loss basis |
| Third-party liability | THB 500,000 | Within the insured premises |
| Compensation for death from fire, explosion or theft | THB 100,000 per person Up to THB 200,000 | The insured and/or family members |
About how much is the Solar Shield solar panel insurance premium?
Annual premium including tax and duty, for a 1-year period of insurance, data as at 20 February 2026, by type of house
| Sum insured | Masonry house (Class 1) From (THB per year) | Half masonry, half timber (Class 2) From (THB per year) |
|---|---|---|
| THB 100,000 | 933.04 | 1,038.97 |
| THB 200,000 | 1,186.63 | 1,397.42 |
| THB 300,000 | 1,439.15 | 1,755.87 |
| THB 400,000 | 1,691.67 | 2,114.32 |
| THB 500,000 | 1,944.19 | 2,472.77 |
| THB 1,000,000 | 3,206.79 | 4,263.95 |
Every figure is a starting premium · The insurer's table offers sums insured from THB 100,000 to THB 5,000,000 in steps of THB 100,000, and you can take 1, 2 or 3 years. A masonry house means a house, townhouse, twin house or residential shophouse with more than 80% brick-and-plaster or concrete walls, while a half masonry, half timber house is 50–80%. The insurer reserves the right to change premiums and cover. The amount you actually pay is the one on your quote.
A worked example to illustrate
A solar system valued at THB 200,000 on a masonry house (hypothetical figure)
Premium from THB 1,186.63 per year, or on average 1,186.63 ÷ 12 = about THB 98.89 per month
Is a single 3-year policy cheaper?
With a sum insured of THB 200,000 on a masonry house, the 3-year premium starts at THB 2,966.04. Paying the 1-year premium in the current table 3 times = 1,186.63 × 3 = THB 3,559.89
3,559.89 − 2,966.04 = THB 593.85 cheaper
How much more do you pay for a higher sum insured?
A simple rule: for a masonry house on a 1-year policy, each THB 100,000 added to the sum insured adds roughly THB 250 to the starting premium. For example, from THB 200,000 to THB 300,000: 1,439.15 − 1,186.63 = THB 252.52 more per year
Who is Solar Shield solar panel insurance for?
- Owners of detached houses, townhouses, twin houses or residential shophouses with rooftop solar used for the home's own electricity
- People who want to insure the solar system on a separate policy, with the sum insured set to the system's value
- People worried about fire or lightning damaging the panels and equipment
- People who want theft and third-party liability cover in the same plan
- People who want to pay once and be covered for 2–3 years
Who should not buy this plan yet?
Homes with solar installed to sell power back to the electricity authority
The application form states the installation purpose as “for use inside the building only, not selling electricity”. This includes homes in the People's Solar programme that sell surplus power back.
Condominiums, apartments or dormitories
This plan does not accept residential condominium units. See Condominium insurance instead
Buildings not used as a residential home
This plan accepts only premises used as a residential home, not shops, offices or factories
Timber houses with less than 50% brick or concrete walls
This plan accepts only Class 1 and Class 2 buildings as defined by the insurer
People who need cover for the house itself and the contents
This plan insures the solar system only. If you do not yet have insurance on the house itself, see Home fire insurance or Viriyah Baan Un Jai home insurance, THB 500
What limitations should you check before deciding?
1) Natural perils are not covered up to the full sum insured
Windstorm, flood, earthquake and hail have limits in the table in the tens of thousands of baht, for example windstorm (extended) THB 20,000. If the system is worth THB 200,000, this limit is 20,000 ÷ 200,000 = 10% of the system's value (hypothetical example)
2) Damage to electrical equipment has a limit of THB 20,000
This limit does not rise with the sum insured you choose
3) The sum insured must match the system's actual value
The application form asks for the installation date, make, model, wattage, number of panels and installed capacity
4) Damage that happened before the cover started is not covered
This includes damage that results from an event before the policy was underwritten
5) The system must be installed to the installation standard
If the solar system differs from what the plan describes, the insurer's underwriter must review it first, and some areas may be closed to new cover
6) You must provide all the information requested on the application form
The application form asks whether the insured premises had a flood or earthquake in the past 5 years, and whether there is fire insurance with another insurer on the same premises and property
What do you need to send to find out the actual premium for the solar system at your home?
Send just 2 things
- The solar installation receipt or quote, showing the make, model, wattage and number of panels
- A photo of the front of the house and the roof showing the panels
Our team will send a written quote back within the business day, showing the sum insured that fits the system's value, the premium including tax and duty, and the period of insurance you choose. We will tell you straight which plan is good value, and explain any differences in conditions before you pay.
LINE Official: @prakanthai · Tel. +66 2 459 2223
Frequently asked questions
Can I take this plan if my solar is in the People's Solar programme?
This plan's application form states that the system must be installed for use inside the building only, not for selling electricity. If the home sells surplus power back to the electricity authority, this plan does not match how the system is used. Send us the system details and our team can help find a closer fit.
I already have home fire insurance. Do I need this plan as well?
It depends on whether your existing policy lists the solar system as insured property and whether the sum insured covers its value. If you take this plan, you must declare the existing fire insurance on the application form. You can send us the schedule page of your existing policy to check first.
Can I take this plan if I rent my home?
The application form lets you state whether you live there as owner or tenant, but the insured solar system must be the property of the insured.
If solar panels are stolen, can I claim?
This plan covers theft with signs of forced entry, snatch robbery and armed robbery, on a first loss basis, for the actual loss up to the sum insured.
What is the longest period of insurance?
Up to 3 years. The premium table offers 1, 2 and 3 years. A single multi-year policy has a lower total premium than paying the 1-year premium in the current table several times.
Who approves claims: Prakanthai.com or Viriyah?
Underwriting and claim payments are decided by Viriyah Insurance. Prakanthai.com, as the broker, helps coordinate and follow up for you.
Notes
The coverage and premium information on this page is based on the plan document and application form for Viriyah Insurance Public Company Limited's Baan Piam Suk home insurance, Solar Shield 2026 plan, version dated 20 February 2026. It is general information and not part of the insurance contract. Premiums and conditions may change as announced by the insurer. Underwriting and claim payments are decided by the insurer. Prakanthai.com is a non-life insurance broker, not an insurer, licence no. 5104000004. Please read the policy and the quote in full before deciding.