AXA SmartCare Essential health insurance for people with group insurance and families with young children, limit up to THB 10 million per illness
- Updated: 21 October 2026
AXA SmartCare Essential health insurance for people with group insurance and families with young children, limit up to THB 10 million per illness
Underwritten by AXA Insurance Public Company Limited. Inpatient-plan premiums start at THB 16,310 per year, or from THB 2,447 per year with a THB 200,000 deductible (including stamp duty). Highlights: many categories of inpatient treatment are paid at actual cost, within a limit of THB 1–10 million per illness.
You spend a few nights in a private hospital and the bill exceeds your company's group insurance limit, so you pay the part above the limit yourself. When you think about adding health insurance, a full-limit plan costs tens of thousands of baht a year.
If you already have group insurance, should you buy a full plan, or a plan with a deductible whose premium is several times cheaper? And what does this plan not pay for?
AXA SmartCare Essential health insurance: who is it for and how much does it cost?
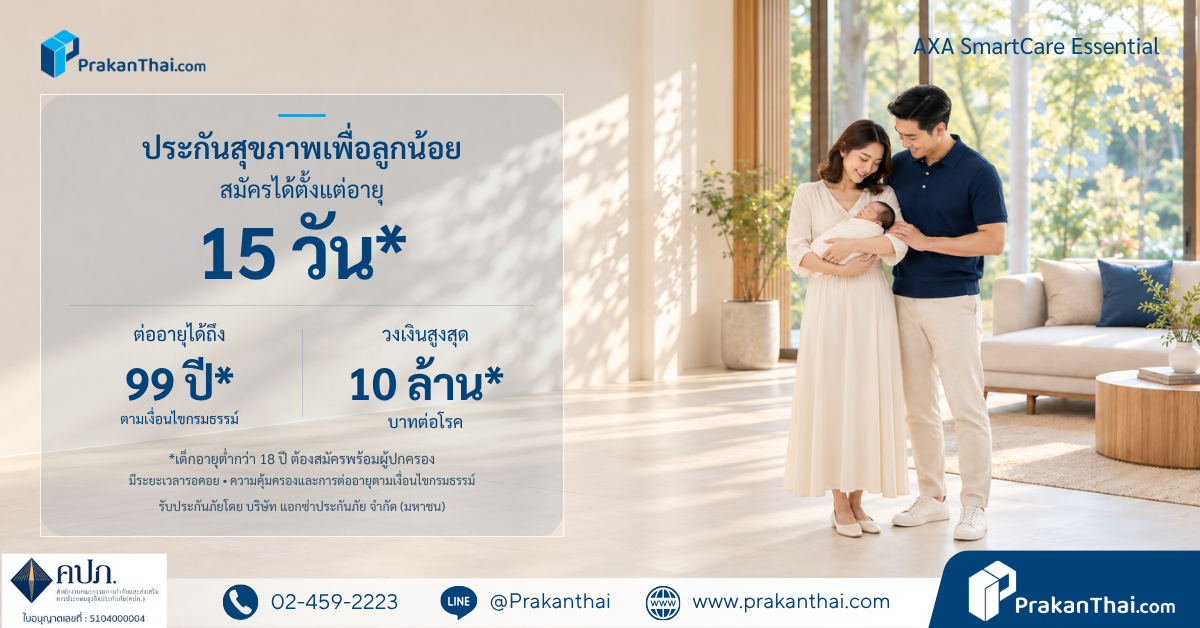
Short answer: AXA SmartCare Essential health insurance from AXA Insurance suits working people who want to top up the limit on their group insurance or state entitlements, and parents who want to insure a child from 15 days old. It covers many categories of inpatient treatment at actual cost, with a limit of THB 1–10 million per illness, and can be renewed up to age 99. Inpatient-plan premiums start at THB 16,310 per year, or from THB 2,447 per year if you choose a THB 200,000 deductible (data as at 20 Oct 2026). The actual premium depends on age, plan, deductible and the additional cover chosen.
What does AXA SmartCare Essential cover?
| Coverage | Plan 1 / Plan 2 / Plan 3 / Plan 4 | Conditions |
|---|---|---|
| Maximum limit per illness | THB 1 / 2 / 5 / 10 million | A repeat stay for the same illness within 90 days of the last discharge counts as one stay |
| Standard room, per day | THB 3,000 / 5,000 / 10,000 / 12,000 | The lowest-priced available standard single room |
| Intensive care (ICU) room, per day | THB 6,000 / 10,000 / 20,000 / 24,000 | – |
| Medicines, diagnostic tests, nursing services and medical supplies | Actual cost | Includes take-home medication of up to 30 days |
| Doctor's visit fees, per day | THB 2,500 / 3,000 / actual cost / actual cost | Once a day |
| Surgery, procedures, surgeon's fees and anaesthetist's fees | Actual cost | Excludes organ transplant surgery |
| Major surgery without a hospital stay (Day Surgery) / minor surgery | Actual cost | – |
| Diagnostic tests before and after a hospital stay | Actual cost | Within 30 days before and after |
| Outpatient treatment after an accident | THB 20,000 / 30,000 / 40,000 / actual cost | Within 24 hours, including 1 follow-up within 30 days |
| Radiotherapy, chemotherapy and cancer treatment | Actual cost | Both inpatient and outpatient |
| Haemodialysis through a blood vessel (chronic kidney failure) | Not covered / Not covered / actual cost / actual cost | – |
| Emergency ambulance | THB 2,000 / 2,000 / actual cost / actual cost | – |
| Private-duty nurse | THB 1,000 per day | Up to 30 days per year |
| Daily cash benefit (chosen instead of claiming treatment costs) | THB 2,000 / 2,500 / 2,500 / 3,500 per day | Up to 31 days per year |
| Funeral expenses | THB 20,000 / 50,000 / 50,000 / 50,000 | Death from illness or injury |
| Death or permanent disability from an accident (Or Bor 2) | THB 50,000 / 80,000 / 100,000 / 120,000 | – |
| Rehabilitation medicine / organ transplant surgery | Not covered | All plans |
"Actual cost" means paying the medically necessary expenses, but the total cannot exceed the plan's limit per illness. There are also emergency assistance services, and cover for inpatient treatment in an emergency while travelling abroad, up to 90 days per trip.
Optional additional cover you can buy
- Outpatient (OPD): choose THB 3,000 per visit (once a day, up to 30 visits per year) or an overall limit of THB 50,000 per year
- Wellness: vaccinations, health check-ups, eye care and dental care, THB 3,000 per year, with a 6-month waiting period
Roughly how much is AXA health insurance?
Annual premium per person, inpatient plan only, with no deductible, including stamp duty. Data as of 20 October 2026
| Age band (years) | Plan 1 / Plan 2 | Plan 3 / Plan 4 |
|---|---|---|
| 0–5 | 48,520 / 57,610 | 64,140 / 70,470 |
| 6–10 | 24,965 / 30,495 | 33,950 / 37,990 |
| 11–15 | 16,310 / 19,940 | 22,475 / 25,660 |
| 16–20 | 16,310 / 19,940 | 22,475 / 24,725 |
| 21–25 | 16,380 / 21,215 | 23,045 / 25,345 |
| 26–30 | 17,400 / 22,660 | 25,225 / 27,750 |
| 31–35 | 18,585 / 23,755 | 27,575 / 31,405 |
| 36–40 | 21,370 / 27,800 | 31,835 / 36,350 |
| 41–45 | 25,175 / 32,755 | 37,965 / 42,440 |
| 46–50 | 29,335 / 38,160 | 43,135 / 48,375 |
| 51–55 | 34,090 / 43,575 | 48,090 / 53,890 |
| 56–60 | 39,590 / 50,610 | 55,855 / 62,595 |
| 61–64 | 49,640 / 60,000 | 66,215 / 74,215 |
If you choose a deductible, the inpatient premium falls as shown in this table. It applies to inpatient benefits only.
| Age band (years) | Deductible THB 20,000 / 40,000 | Deductible THB 100,000 / 200,000 |
|---|---|---|
| 0–40 | Discount 45% / 55% | Discount 75% / 85% |
| 41–60 | Discount 30% / 40% | Discount 65% / 75% |
| 61 and over | Discount 10% / 15% | Discount 30% / 35% |
Other discounts: 5% off when 2–3 people apply together, 10% off for 4 or more, and a 5% discount at renewal in a year with no claims. The actual premium depends on age, plan, deductible, additional cover and the insurer's underwriting decision. The amount you pay is as shown on the quote.
To see the premium for your whole household with the family discount and stamp duty included, enter your ages in the AXA SmartCare Essential premium calculator right away.
A worked example to illustrate
Age 30, already has group insurance: Plan 1 with no deductible costs THB 17,400 per year. With a THB 200,000 deductible it falls to THB 2,611 per year, a difference of THB 14,789 per year. If you are admitted to hospital and eligible treatment costs total THB 350,000, the first THB 200,000 is borne by the insured (and can be claimed from group insurance), and AXA considers paying the remaining THB 150,000 within Plan 1's sub-limits. Or, if you do not claim treatment costs, you can choose the daily cash benefit instead, for example 4 days × THB 2,000 = THB 8,000, with no deductible applied.
If you want OPD added: at age 26–30, Plan 1 goes from THB 17,400 to THB 27,770 with OPD of THB 3,000 per visit (an extra THB 10,370), or to THB 29,920 with OPD of THB 50,000 per year (an extra THB 12,520).
Family of 3, Plan 2: the father aged 35 and the mother aged 33 pay THB 23,755 each, and the child aged 4 pays THB 57,610, a total of THB 105,120. After the 5% family discount, that is about THB 99,864 per year.
This is an illustration only. The amount actually paid depends on the insurer's assessment. A simple rule: choose the plan by the room rate at the hospital you normally use, then choose a deductible no higher than what your other insurance can pay.
Who is AXA SmartCare Essential for?
- Working people who already have one group or other health insurance policy and want a limit in the millions on top, at a premium reduced by the deductible
- People who use social security or the gold card (Universal Coverage Scheme) and want the option of treatment at a private hospital
- Parents who want health insurance for a child from 15 days old, together with themselves on the same plan, and the family discount
- People who want a daily cash benefit while in hospital, or OPD cover for general doctor visits, using an inpatient plan with a high deductible to keep the total premium down
Who should not buy this plan yet?
- People with chronic conditions or a history of treatment for certain conditions. Pre-existing conditions, or conditions not yet cured, are not covered, and in some cases AXA does not accept the application at all, for example a history of cancer even if cured, type 1 diabetes, heart disease or a stent, depression or anxiety, 2 or more chronic conditions, or a BMI above 34.99 or below 15.99.
- People in occupations AXA does not accept, such as doctors, nurses, pharmacists, dentists, soldiers, police officers, judges, public prosecutors, Ministry of Public Health officials, construction workers, actors, politicians, professional athletes, lawyers, security guards, truck drivers, motorcycle taxi riders and people who work in nightlife venues.
- Age 65 and over. This plan accepts new applicants up to age 64 years 364 days.
- People who need rehabilitative physiotherapy after leaving hospital, or organ transplant surgery costs. No plan covers these, and Plans 1–2 do not cover dialysis.
- Parents who want to insure only one child. A child under 18 must apply together with at least one parent on the same plan.
What limitations should you check before deciding?
- 30-day waiting period: illness in the first 30 days after the policy first takes effect is not covered, except injury from an accident.
- 120-day waiting period for tumours, cysts, cancers of any kind, haemorrhoids, hernias of any kind, pterygium or cataracts, removal of the tonsils or adenoids, stones of any kind, varicose veins in the legs, and endometriosis.
- Your health history may lead to exclusions for specific conditions. For example, if you have been treated for high blood pressure, blood pressure and its complications such as coronary artery stenosis or stroke may be excluded; or if you have had allergies, allergic rhinitis and allergic asthma may be excluded.
- The limit is per illness, not per year, and Plans 1–2 have sub-limits for room, doctor's fees and ambulance. If you choose a room that costs more than the limit, you pay the difference yourself.
- The deductible is applied per illness and applies to inpatient only. If no other insurance pays this part for you, you pay it yourself every time you are admitted to hospital, and each time you must choose either to claim treatment costs (deductible applied) or the daily cash benefit (no deductible applied), not both.
- Premiums are adjusted by age band, and the discount from the deductible shrinks as you get older. For example, Plan 1 with a THB 200,000 deductible costs THB 9,898 at age 56–60 but THB 32,267 at age 61–64.
- At age 61 or over you must attach health check results according to the insurer's list, unless you choose the THB 200,000 deductible.
- In some cases you pay upfront. At AXA's network hospitals you can be treated with your card without paying upfront, but if the insurer needs to review additional test results, it may ask you to pay first and send the claim documents afterwards.
If you want an inpatient plan with a simpler structure to compare, see Bangkok Insurance inpatient health insurance, or if you are worried about the costs of cancer treatment other than doctors' fees, see lump-sum cancer insurance.
What do you need to tell us to find out the premium for yourself or your family?
Tell us just 3 things
- Date of birth of everyone to be insured
- Height and weight
- Any chronic conditions or treatment history in the past 5 years, and whether you already have group insurance or other health insurance
Our team will calculate using AXA's quotation program and send back a premium quote comparing 2–3 options (for example no deductible / THB 200,000 deductible / with OPD added) within a business day, telling you straight which exclusions a history like yours is likely to meet, before you pay. Or buy online through AXA Insurance's system.
LINE Official: @prakanthai · Tel. +66 2 459 2223
Frequently asked questions
Can a 2-month-old baby be insured with AXA health insurance?
Yes. This plan accepts children from 15 days old, but they must apply together with a parent on the same plan. A child under 1 year old must attach the discharge summary from the birth and a copy of the birth certificate signed by the guardian.
Do I need a medical check-up before applying?
Up to age 60 no health check is needed, but you must answer every health question on the application form truthfully. At age 61 or over you must attach health check results, unless you choose the THB 200,000 deductible.
If you already have group insurance, how do you claim on both?
Claim from group insurance first, then bring the part that exceeds it to claim from AXA. If you need the original documents returned to claim with another insurer, state this on the claim form. The deductible you choose should be close to what group insurance can pay for each hospital stay.
If you claim a lot, will you have to co-pay next year?
No. Copayment depends on the conditions of each plan's policy, and AXA SmartCare Essential has no copayment condition, either at purchase or at renewal. The premium in later years is adjusted by age band, and in a year with no claims you get a 5% renewal discount.
If I'm admitted to hospital, do I have to pay upfront?
At AXA's network hospitals, show your ID card together with your AXA HealthCare card for both inpatient and outpatient treatment. At a hospital outside the network, pay first and then send the claim documents. For bills of up to THB 10,000, you can send a colour scan by email to [email protected]. For bills over THB 10,000, send the original documents by post.
Can I pay the premium in instalments?
The premium is paid annually. If you pay by credit card, you can ask to split the payment through the card-issuing bank's app, subject to the bank's conditions.
Can foreigners living in Thailand buy it?
Yes. Use a certified copy of your passport. Some nationalities must also attach a copy of their latest visa and the first page of a Thai bank passbook. If you plan to use the insurance to support a visa application, tell our team first, because each type of visa sets different policy conditions. Read more at O-A Visa Health Insurance Thailand: How Much Cover You Need
Who approves underwriting and claims?
Underwriting and claim payments are decided by AXA Insurance. As your broker, Prakanthai.com helps coordinate and follows up for you.
Notes
The coverage and premium information on this page is based on the product presentation and the health and personal accident insurance premium calculator for SmartCare Essential from AXA Insurance Public Company Limited, checked on 20 October 2026. It is general information and not part of the insurance contract. Premiums and conditions may change as the insurer announces. Underwriting and claim payments are decided by the insurer. Prakanthai.com is a non-life insurance broker, not an insurer, licence no. 5104000004, providing services since 2004. Please read the policy and the quote in full before deciding.