
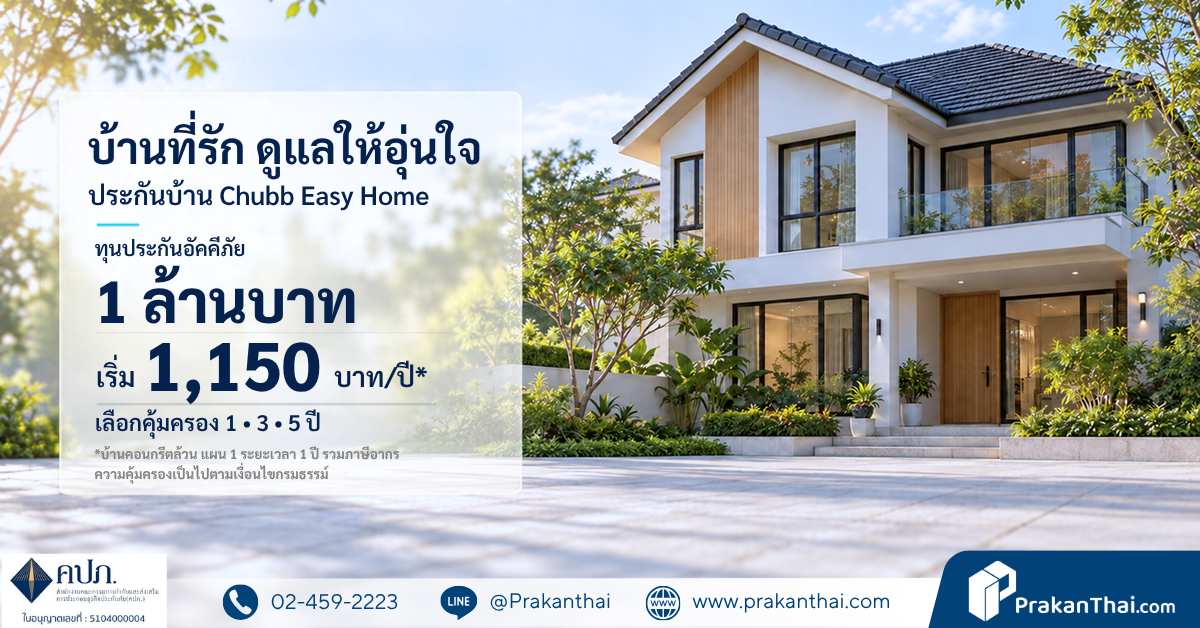
Chubb Easy Home insurance, THB 1 million sum insured, from THB 1,150 per year
- Published: 12 October 2026
Chubb Easy Home insurance, THB 1 million sum insured, from THB 1,150 per year
Premium data as of 11 October 2026 · compiled by Prakanthai.com
Underwritten by Chubb Samaggi Insurance Public Company Limited
Premiums from THB 1,150–9,800, depending on the plan, building materials and a term of 1, 3 or 5 years, including tax and stamp duty
Highlights: THB 1 million sum insured, claims paid at new replacement value with no deduction for depreciation, and a 24-hour home emergency repair service
The pipe under the sink burst at eight in the evening and water flooded the kitchen. None of the local repairmen were free, and by the time it was fixed, half the row of wooden kitchen cabinets had swollen.
How much does home insurance with both fire cover and an emergency repair service like this cost, and how far does it cover flood?
Chubb Easy Home insurance: who is it for and how much is the premium?
In short: Chubb Samaggi Insurance's Chubb Easy Home insurance suits owners of detached houses, townhouses or town homes that they actually live in, whether concrete or half-concrete, half-timber. It gives THB 1,000,000 for fire and additional perils, THB 20,000 in total for natural disasters, THB 20,000 for burglary, and emergency repairs 2 times a year. The premium is from THB 1,150 per year for a concrete house on Plan 1 (as at 11 October 2026). The actual premium depends on the plan, building materials and period of cover.
What does Chubb Easy Home insurance cover?
| Coverage | Plan 1 / Plan 2 | Conditions |
|---|---|---|
| Fire, lightning, explosion, vehicle impact, aircraft, water damage other than flood | THB 1,000,000 | Actual loss |
| Natural disasters (windstorm, flood, earthquake, tsunami, hail) | Up to THB 20,000 for all perils combined | Not drawn from the THB 1 million limit |
| Burglary | THB 20,000 | Requires signs of forced entry, or robbery / gang robbery |
| Temporary accommodation rent | Concrete house: THB 1,000 per day, up to THB 100,000 per year in total Half-concrete, half-timber: THB 500 per day, up to THB 50,000 per year in total | Does not apply to condominiums |
| Personal liability to third parties | Plan 1: none / Plan 2: THB 200,000 | Both in and outside the home, within Thailand |
| 24-hour home emergency repairs (Home Assistance) | Technician's labour and travel costs, up to THB 1,000 per call-out | Up to 2 times per year |
Emergency repairs cover electricians, plumbers, roof, ceiling and glass repairs, locksmiths, air-conditioner, fridge and water-heater technicians, and removal of dangerous animals from the home. Spare parts and materials are subject to the service conditions.
Roughly how much is the premium for Chubb Easy Home insurance?
Premiums include tax and stamp duty, as at 11 October 2026
| Building materials / term | Plan 1 | Plan 2 |
|---|---|---|
| All concrete / 1 year | 1,150 | 1,400 |
| All concrete / 3 years | 3,280 | 4,015 |
| All concrete / 5 years | 5,200 | 6,360 |
| Half-concrete, half-timber / 1 year | 1,990 | 2,200 |
| Half-concrete, half-timber / 3 years | 5,500 | 6,200 |
| Half-concrete, half-timber / 5 years | 9,000 | 9,800 |
Every figure in the table is a starting premium. The actual premium depends on the plan, building materials, term and the insurer's underwriting decision, as stated in the quote.
Worked example: how much more does Plan 2 cost, and how much do you save with a 5-year policy?
Say the house is concrete
- Plan 2 costs 1,400 − 1,150 = THB 250 per year more than Plan 1 and adds THB 200,000 of third-party liability cover
- Plan 1 renewed every year for 5 years: 1,150 × 5 = THB 5,750, against THB 5,200 for a 5-year policy, a difference of THB 550
- Plan 2 renewed every year for 5 years: 1,400 × 5 = THB 7,000, against THB 6,360 for a 5-year policy, a difference of THB 640
This is an illustration only, assuming the annual premium stays the same throughout. The simple rule: Plan 2 costs little extra per year, so if your neighbours live right next door or several people live in your house, Plan 2 gives you more help with liability.
Who is Chubb Easy Home insurance for?
- Owners of detached houses, townhouses or town homes they live in, whether all concrete or half-concrete, half-timber
- People who want an emergency technician to help when the power goes out, a pipe bursts, keys are lost or the air conditioner breaks down
- People who want liability cover towards neighbours for an extra THB 250 per year (Plan 2, concrete house)
- People who want to lock in cover for 3 or 5 years
- Condominium owners who want cover for furniture and belongings in the unit
Who should not buy this plan yet?
- All-timber houses: this plan does not insure all-timber houses
- Homes in flood-risk areas, or people who want a high flood limit: flood comes under the combined natural disaster limit of up to THB 20,000, and the insurer reserves the right not to insure in flood-risk zones. See Thaivivat home and condominium insurance, with THB 100,000 flood cover
- Homes that would cost more than THB 1 million to rebuild, where you want a sum insured matching the real value: this plan's main sum insured is fixed at THB 1,000,000
- People who want cover for the condominium structure: for condominiums, only furniture and belongings in the unit are covered, not the building or common areas
- People with many valuables at home who are worried about burglary: the burglary limit is THB 20,000
Limits to check before you decide
- Flood does not come under the THB 1 million sum insured. All 5 natural disaster perils share a combined limit of up to THB 20,000.
- Burglary must meet the conditions: there must be signs of forced entry to the building, or it must be a robbery or gang robbery. The limit is THB 20,000.
- Temporary accommodation rent does not apply to condominiums
- Emergency repairs pay labour and travel costs up to THB 1,000 per call-out, 2 times a year. Spare parts and any amount above the limit are subject to the service conditions.
- The THB 1 million sum insured is the maximum limit. The insurer pays the actual loss, not a lump sum for every incident.
- You must declare how the building is used and where it is located accurately. Incorrect information may affect the claim assessment.
Claim strengths under the product conditions: the under-insurance condition is waived, claims are paid at new replacement value with no deduction for depreciation, and Fast Track Claim covers eligible damage up to THB 30,000, paid within 15 days of the date the claim amount is agreed.
What do you need to send to find out whether your house can be insured?
Send just 3 things
- Type of home, e.g. detached house, townhouse or condominium
- Building materials: all concrete or half-concrete, half-timber
- District and province of the property
Our team will check whether the house meets the underwriting conditions and send you a written quote within a business day, showing the Plan 1 and Plan 2 premiums for 1, 3 and 5 years. You don't need to send any personal documents at this stage. If a plan is good value, we will tell you straight. If the conditions differ, we will explain the differences before you pay.
LINE Official: @prakanthai · Tel. +66 2 459 2223
Frequently asked questions
My house is mortgaged and already has fire insurance through the bank. Can I buy more?
Send your existing policy to our team first so we can check what it covers and what is still missing. Having several policies does not mean you can be paid more than the actual loss.
What does “paid at new replacement value, with no deduction for depreciation” mean?
If an insured item is damaged, the insurer assesses the claim on the price of a new replacement, without reducing it for the age of the original item, up to the limits and subject to the conditions in the policy.
If I call out an emergency technician, who pays for spare parts?
The insurer pays the technician's labour and travel costs up to THB 1,000 per call-out. Spare parts, materials and any amount above the limit are subject to the service conditions.
Which cases qualify for Fast Track Claim?
Eligible damage worth up to THB 30,000. The insurer pays within 15 days of the date the insurer and the insured agree the claim amount.
If I want higher flood cover, which plan can I compare?
You can compare it with Thaivivat home and condominium insurance, which has a THB 100,000 flood limit and a choice of sum insured from THB 1–5 million
Who approves claims: Prakanthai.com or Chubb?
Underwriting and claim payments are decided by Chubb Samaggi Insurance. As your broker, Prakanthai.com helps coordinate and follows up on your case.
Notes
The coverage and premium information on this page is based on product information for Chubb Easy Home from Chubb Samaggi Insurance Public Company Limited as at 11 October 2026. It is general information and not part of the insurance contract. Premiums and conditions may change as announced by the insurer. Underwriting and claim payments are decided by the insurer. Prakanthai.com is a non-life insurance broker, not an insurer, licence no. 5104000004, providing services since 2004. Please read the policy and the quote in full before deciding.