
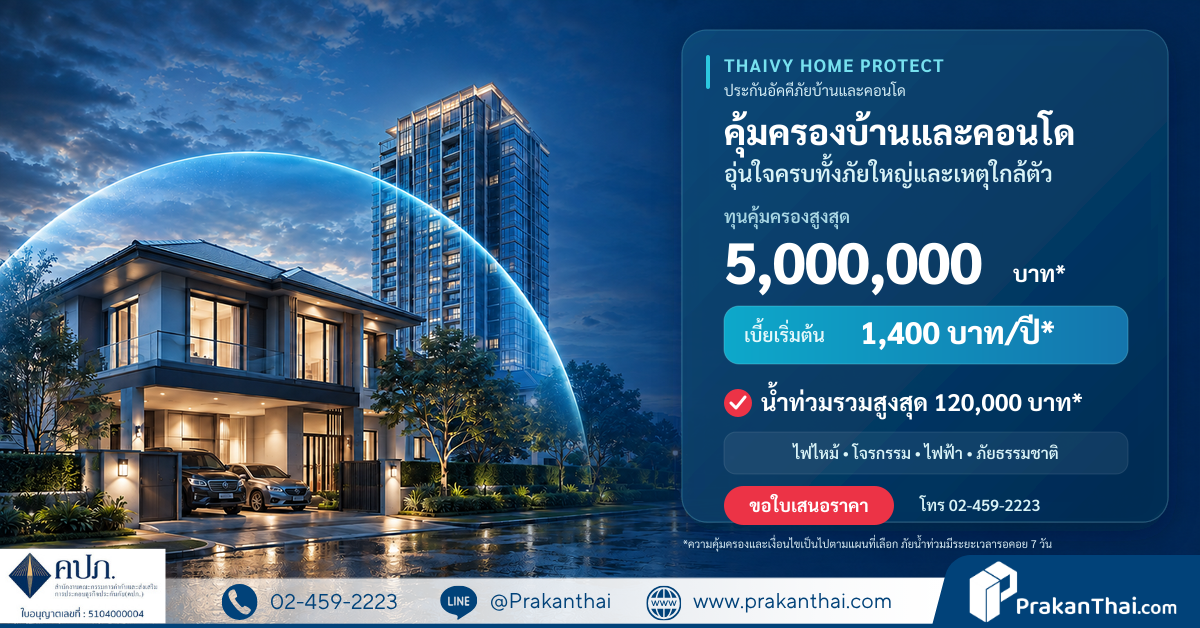
Thaivivat home and condominium insurance, sum insured THB 1–5 million, from THB 1,400
- Published: 11 October 2026
Thaivivat home and condominium insurance, sum insured THB 1–5 million, from THB 1,400
Premium data as of 11 October 2026 · compiled by Prakanthai.com
Underwritten by Thaivivat Insurance Public Company Limited
Starting premiums of THB 1,400–33,080, depending on the plan, the building type and a period of 1, 3 or 5 years, incl. stamp duty and tax
Highlights: sum insured of THB 1–5 million, covering both the house and its contents, with flood, burglary and EV Charger cover
You took out home insurance when you got your bank loan, but when you actually open the policy, it covers only the building. The furniture, air conditioners, TV and the EV charger you have just installed are not in the policy at all.
If you want home insurance that also covers your contents and flood, what sum insured should you choose, and what is still not covered?
Who is THAIVY HOME PROTECT home and condominium insurance for, and how much is the premium?
In short: Thaivivat's THAIVY HOME PROTECT home and condominium insurance suits owners who actually live in their house or condominium and want cover for both the building and its contents. The sum insured is THB 1–5 million, with flood cover of THB 100,000, burglary, electrical appliances and liability to neighbours. Premiums start at THB 1,400 per year for a concrete building with a sum insured of THB 1 million (as at 11 October 2026). The actual premium depends on the sum insured, the building type and the period of cover.
What does THAIVY HOME PROTECT home insurance cover?
Coverage Limit, Plan 1 → Plan 5 (THB) Conditions Fire, lightning, explosion, vehicle impact, aircraft, water damage other than flood 1,000,000 → 5,000,000 Main sum insured, excluding foundations Flood 100,000 on all plans 7-day waiting period when first insured Windstorm / hail / earthquake, volcanic eruption, tsunami 100,000 → 500,000 per peril – 4 basic natural perils 20,000 in total per year Windstorm, flood, earthquake, hail Burglary (burglary form 2) 25,000 → 125,000 Signs of forced entry or use of force required Electrical equipment and appliances 25,000 → 125,000 – Electric vehicle charger (EV Charger) 20,000 In total over the period of insurance Glass 20,000 on all plans – Third-party liability 100,000 → 500,000 Legal liability Compensation if the insured dies from an incident at the insured premises 100,000 on all plans – Temporary accommodation rent Concrete house: 1,000 per day, up to 100,000 in total
Half-concrete, half-timber: 500 per day, up to 50,000 in total When fire damage exceeds 50% and the home cannot be lived in
| Coverage | Limit, Plan 1 → Plan 5 (THB) | Conditions |
|---|---|---|
| Fire, lightning, explosion, vehicle impact, aircraft, water damage other than flood | 1,000,000 → 5,000,000 | Main sum insured, excluding foundations |
| Flood | 100,000 on all plans | 7-day waiting period when first insured |
| Windstorm / hail / earthquake, volcanic eruption, tsunami | 100,000 → 500,000 per peril | – |
| 4 basic natural perils | 20,000 in total per year | Windstorm, flood, earthquake, hail |
| Burglary (burglary form 2) | 25,000 → 125,000 | Signs of forced entry or use of force required |
| Electrical equipment and appliances | 25,000 → 125,000 | – |
| Electric vehicle charger (EV Charger) | 20,000 | In total over the period of insurance |
| Glass | 20,000 on all plans | – |
| Third-party liability | 100,000 → 500,000 | Legal liability |
| Compensation if the insured dies from an incident at the insured premises | 100,000 on all plans | – |
| Temporary accommodation rent | Concrete house: 1,000 per day, up to 100,000 in total Half-concrete, half-timber: 500 per day, up to 50,000 in total | When fire damage exceeds 50% and the home cannot be lived in |
Limits shown as "Plan 1 → Plan 5" rise with each plan's main sum insured. Actual payment depends on the cause of the loss, the exclusions and the excess (deductible) in the policy.
Roughly how much is the home and condominium insurance premium?
Premiums include stamp duty and VAT. Information as at 11 October 2026.
House or condominium with a concrete structure
Plan (main sum insured) 1 year 3 years / 5 years Plan 1 (THB 1 million) 1,400 3,500 / 4,880 Plan 2 (THB 2 million) 2,260 5,650 / 7,885 Plan 3 (THB 3 million) 3,190 7,975 / 11,133 Plan 4 (THB 4 million) 4,120 10,299 / 14,376 Plan 5 (THB 5 million) 5,170 12,923 / 18,041
| Plan (main sum insured) | 1 year | 3 years / 5 years |
|---|---|---|
| Plan 1 (THB 1 million) | 1,400 | 3,500 / 4,880 |
| Plan 2 (THB 2 million) | 2,260 | 5,650 / 7,885 |
| Plan 3 (THB 3 million) | 3,190 | 7,975 / 11,133 |
| Plan 4 (THB 4 million) | 4,120 | 10,299 / 14,376 |
| Plan 5 (THB 5 million) | 5,170 | 12,923 / 18,041 |
Half-concrete, half-timber house
Plan (main sum insured) 1 year 3 years / 5 years Plan 1 (THB 1 million) 2,230 5,570 / 7,780 Plan 2 (THB 2 million) 4,020 10,050 / 14,030 Plan 3 (THB 3 million) 5,850 14,630 / 20,420 Plan 4 (THB 4 million) 7,670 19,170 / 26,760 Plan 5 (THB 5 million) 9,480 23,700 / 33,080
| Plan (main sum insured) | 1 year | 3 years / 5 years |
|---|---|---|
| Plan 1 (THB 1 million) | 2,230 | 5,570 / 7,780 |
| Plan 2 (THB 2 million) | 4,020 | 10,050 / 14,030 |
| Plan 3 (THB 3 million) | 5,850 | 14,630 / 20,420 |
| Plan 4 (THB 4 million) | 7,670 | 19,170 / 26,760 |
| Plan 5 (THB 5 million) | 9,480 | 23,700 / 33,080 |
Every figure is a starting premium. The actual premium depends on the sum insured, the building type, the period of cover and the insurer's underwriting decision. The quote is what counts.
Worked example: how much do you save with a 3-year or 5-year policy compared with renewing every year?
Say you have a concrete house and choose Plan 2, with a sum insured of THB 2 million
- Renewing every year for 3 years: 2,260 × 3 = THB 6,780, compared with THB 5,650 for a 3-year policy. A difference of THB 1,130
- Renewing every year for 5 years: 2,260 × 5 = THB 11,300, compared with THB 7,885 for a 5-year policy. A difference of THB 3,415
This is an illustration that assumes the annual premium stays the same throughout. A simple rule: if you are sure you will stay in this home for several years, a multi-year policy costs less in total, but you pay it as one lump sum up front.
Who is THAIVY HOME PROTECT home insurance for?
- Owners of detached houses, semi-detached houses, townhomes or condominiums that they actually live in
- People who already have home insurance through a home loan, but whose existing policy does not include contents
- Homes with many electrical appliances, or with an EV Charger installed
- Townhomes or condominiums where fire or water could spread to the unit next door, for owners who want a liability limit for their neighbours
- People who want to lock in cover for 3 or 5 years in one go
Who should not buy this plan yet?
- Homes left unoccupied for more than 60 days in a row, such as holiday homes, homes waiting to be sold or empty units. This product does not cover that case.
- People who want cover for cash, gold, gemstones, wristwatches or collectibles. These items are excluded.
- Homes in areas that flood every year and need a high flood limit. The flood limit is THB 100,000 on every plan.
- Homes that already have a THAIVY HOME PROTECT policy. Each insured home can have only 1 policy.
- Buildings used as a shop or business. This plan is designed for homes; see SME shop insurance instead.
Limits to check before you decide
- Flood has a 7-day waiting period when you first take out the insurance. Damage during this period is not covered, so don't wait for a flood warning before you buy.
- Foundations are not covered, and neither is the value of the land, so the sum insured should not be set at the home's sale price.
- Burglary under burglary form 2 requires signs of forced entry or of force used to get into the home. Items that go missing without any such signs do not qualify.
- The 4 basic natural perils together are capped at THB 20,000 per year. For the separate per-peril limits in the table, check each peril's definition in the policy.
- EV Charger cover is capped at THB 20,000 in total over the period of insurance, not per year, and covers only overloading, overvoltage or a short circuit.
- Temporary accommodation rent is paid when fire damage exceeds 50%, and only when the home cannot be lived in.
If you have a condominium unit and want to compare this with a plan designed specifically for condominiums, see condominium insurance.
Want to know what sum insured suits your home and what you need to send?
Send just 3 things
- The building type, e.g. concrete house, condominium or half-concrete, half-timber
- The value of the building excluding the land, and the approximate value of your contents
- The schedule page of your existing home insurance policy (if you have one)
Our team will send you a written quote within a business day, showing the plan whose sum insured fits your home, the premiums for 1, 3 and 5 years, and where your existing policy overlaps with the new plan. If a plan is good value, we will tell you straight. If the conditions differ, we will explain the differences before you pay.
LINE Official: @prakanthai · Tel. +66 2 459 2223
Frequently asked questions
Should the sum insured match the price you paid for the home?
No need. The sale price includes the value of the land, which is not covered. Base it on the cost of rebuilding the building plus the value of your contents.
Is a leak from the unit above or a burst water pipe covered?
The main cover includes water damage other than flood, but payment depends on the cause: deterioration, continuous seepage or lack of maintenance, for example, may be excluded. Send the details of the incident to our team so we can check it first.
Can you claim if your air conditioner or fridge is damaged by a power surge?
Electrical appliances are covered up to the plan's limit, but not for deterioration or breakdown from normal use.
You already have home insurance through your bank. Can you buy another policy?
Yes, but first compare whether your existing policy covers only the building or already includes your contents, so you don't pay twice for cover you already have.
What should you do first if your home is damaged?
Contain the incident as far as you safely can, notify the insurer or our team as soon as possible, take photos and videos of the damage before moving anything, and keep the damaged items for inspection. Don't throw them away or make permanent repairs before the insurer approves.
Who approves claims: Prakanthai.com or Thaivivat?
Underwriting and claim payments are decided by Thaivivat. Prakanthai.com, as your broker, helps coordinate and follow up for you.
Notes
The coverage and premium information on this page is based on Thaivivat Insurance Public Company Limited's product information for THAIVY HOME PROTECT as at 11 October 2026. It is general information and not part of the insurance contract. Premiums and conditions may change as announced by the insurer. Underwriting and claim payments are decided by the insurer. Prakanthai.com is a non-life insurance broker, not an insurer, licence no. 5104000004, providing services since 2004. Please read the policy and the quote in full before deciding.