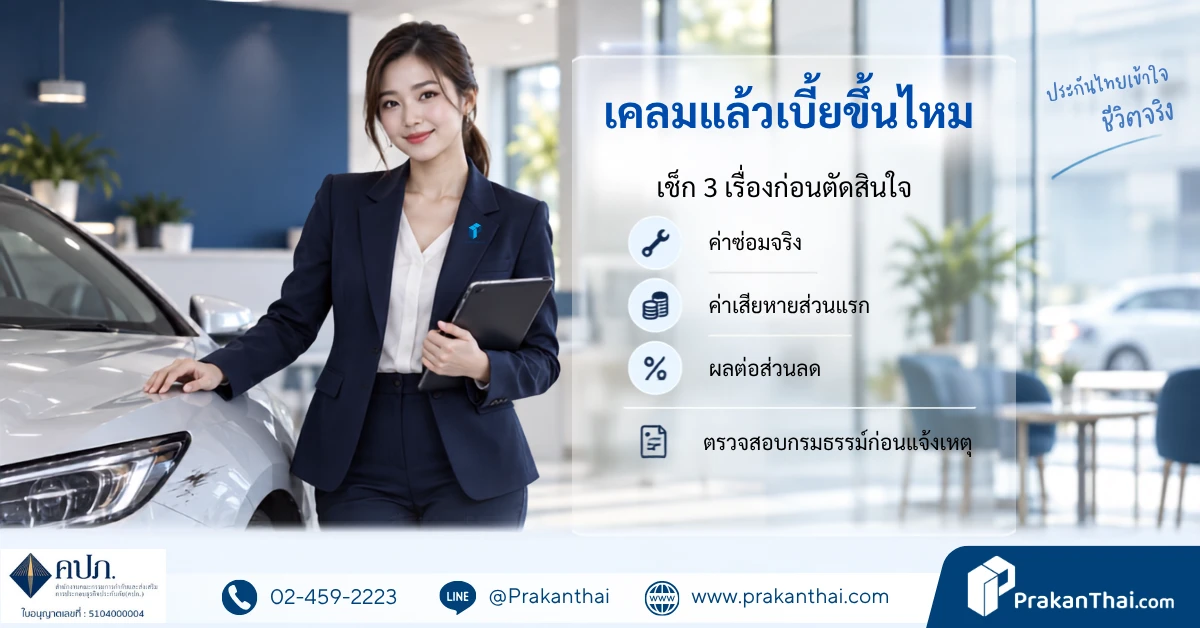
Does making a claim raise your premium? Which claims affect your car insurance discount?
- Published: 8 September 2026
- Category: Insurance guides
Does making a claim raise your premium? Which claims affect your car insurance discount?
A claim doesn't always mean a higher premium next year. If you were not at fault and the party legally liable can be identified, the claim does not cost you your no-claims discount under the policy conditions. But a claim where you were negligent, or where the other party can't be identified, may affect your discount when you renew your car insurance.
Don't pay for repairs yourself just because you're afraid your premium will go up. Separate the two questions clearly: how much you have to pay this time, and which discounts will change at renewal.
Which claims affect your no-claims discount?
The no-claims discount, or NCB, is a premium discount based on the car's claims history. For policies that use this condition, the key principles are:
| Incident | Effect on the no-claims discount |
|---|---|
| You were not at fault, and the liable party can be identified | This claim does not cost you your discount under the conditions |
| You negligently hit another car, or drove into a post yourself | Your discount may be reduced under the rules; it depends on your record and the policy conditions |
| Hit and run, and the liable party can't be identified | You may lose your discount even though you were not at fault |
Reductions in the discount also depend on the number of claims and the amount of the loss, so don't assume that “one claim raises everyone's premium by the same amount”. Plans with different conditions or endorsements need to be checked separately against that cover.
A right worth knowing: when you were not at fault and the liable party was identified, giving the insurer the right to recover its costs, the insurer failing to actually recover the money is not a reason to cut your no-claims discount for that claim.
If you hit a post yourself, do you have to pay a THB 1,000 excess?
Not always, and it is a separate matter from next year's discount.
For damage covered by Class 1 insurance, if you hit a post or a wall and the car or its equipment is dented, broken or cracked, and you can clearly state what happened, the date, the time and the place, you do not have to pay THB 1,000 just because no other vehicle was involved.
But if only the paintwork is damaged, you can't state the cause, or the policy sets another excess, the conditions need to be checked separately.
Before you pay, ask plainly: “Which clause of the policy is this excess charged under?” so you understand both the amount and the reason, rather than going only on the words “no other party”.
After a claim, don't look only at the no-claims discount
Eligible private car policies may also have a driving behaviour discount, which is separate from the NCB. An accident caused by negligence may therefore affect both, and each is adjusted under different rules.
So don't add up the percentages of different discounts yourself, or conclude that one claim will cost you every discount. Check all the discount items on the policy and the renewal quote before comparing.
Small scratches: claim, or pay for the repair yourself?
Don't use a single repair-cost figure as the rule for every car. Before choosing to pay yourself, we recommend checking these three things:
- Is it covered, and what will the repair really cost? Have the damage assessed first; don't judge by the size of the mark alone.
- What will you have to pay this time? Ask for details of the excess and anything not covered.
- Which discounts might change at renewal? Have the insurer or your broker check against the policy and your actual record, keeping estimates separate from prices the insurer has confirmed.
When an incident happens, notify your insurer without delay and report the facts truthfully. Collect evidence when it is safe to do so, don't hold off reporting while you work out whether claiming is worth it, and then go through your repair options and entitlements with the insurer.
Frequently asked questions
If you were not at fault and keep your discount, will next year's premium stay the same?
Not necessarily, because the no-claims discount is calculated on the premium for the renewal year, not on what you paid last year. When the basis of calculation or the cover changes, the amount you pay can change, even if your discount percentage stays the same.
Before concluding that it's more expensive because of the claim, compare the sum insured, the repair terms, the excess and the discounts between the old offer and the new one.
Do Class 2+, Class 3+ and natural disaster claims all follow the same rules?
Don't generalise. Some endorsements state that the good-record premium discount and the bad-record premium loading do not apply to that additional cover. So you need to check which section the claim falls under and which endorsement applies, rather than judging by the insurance class alone.
Not sure how much of this claim you'll have to pay? Let Prakanthai check
Don't give up your right to claim just because someone tells you “if you claim, your premium will definitely go up”.
Let the Prakanthai.com team check the conditions, explain the excess and liaise to check the effect on your discount, or help compare renewal quotes based on your details.
💬 Message LINE Official @prakanthai
Type “check claim” with your insurance class and a short description of what happened. Our team will ask for any further details needed by private message.
☎️ Call +66 2 459 2223
🌐 Prakanthai.com
Know your rights before you decide, so you don't end up paying yourself out of worry alone.
This article explains general principles. Cover and discounts depend on the facts, the policy, its endorsements and the relevant rules. An initial assessment is not confirmation of your renewal premium or of a claim approval.
Updated: 8 September 2026