By Prakanthai.com | 17 November 2026
When we opened the business, we probably worked out how much we had to sell each month to cover the rent, salaries and stock.
But have you ever looked at it from the other side? If the shop had to close tomorrow, or the company could not work for a month, how long would the money you have last?
This is a question worth asking before you choose SME business insurance, because it shows which risks you can carry yourself and which are too heavy for the business to absorb on its own.
After one loss, how many months of profit does it take to earn it back?
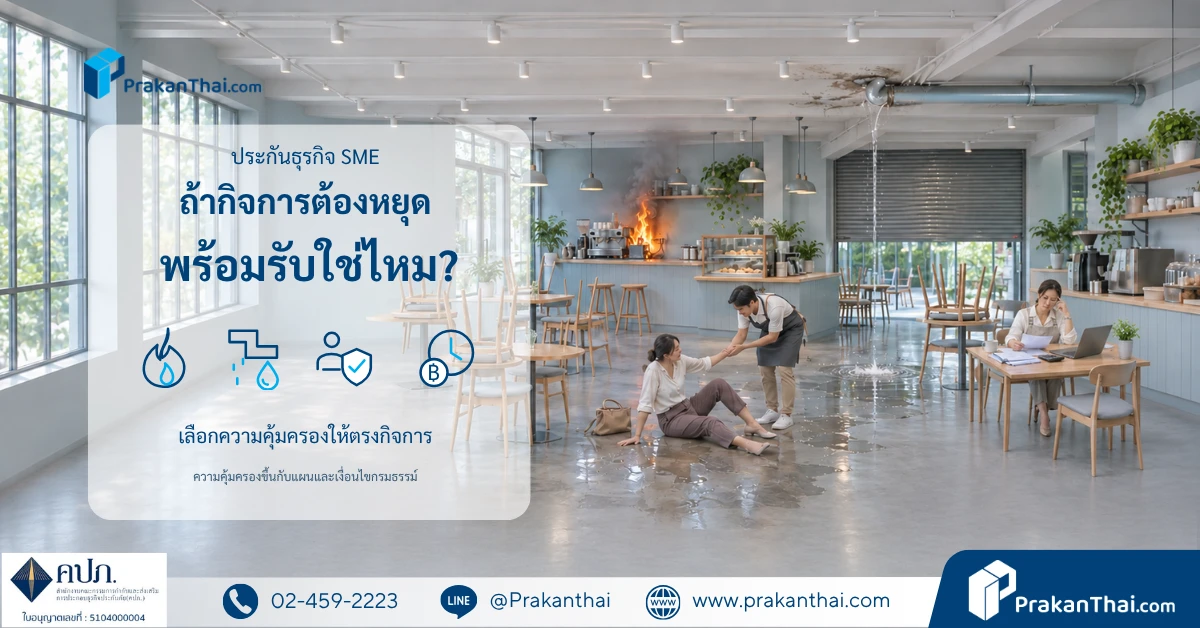
Suppose the business makes a net profit of THB 100,000 a month. One day a fire breaks out and equipment and stock worth THB 2 million in total are damaged.
That THB 2 million equals 20 months of profit, and that is before counting the income lost while the premises are closed for repairs and the costs you still have to pay.
Money you had set aside to buy more stock, open another branch or keep as a reserve may have to go on replacing equipment and refitting the shop.
Fire insurance or property insurance can help with the cost of repair or replacement when the property and the cause of the damage are covered. How much it pays depends on the sum insured, the sub-limits and the conditions of the plan you hold.
And who helps pay the rent and salaries while the shop is closed?
Once the shop is repaired it may be able to reopen, but in the meantime the owner still has many costs to cover.
This is where business interruption insurance comes in, because property insurance on its own does not automatically compensate for lost income.
If you have this cover, it may help compensate for lost profit and fixed costs such as rent or salaries, up to the limit and for the period set. Generally it must result from damage to property caused by a peril the policy covers.
When you ask for a quote, add one more question: “If an incident forces the business to stop, how does this plan help with the costs during that time?”
If a customer has an accident in the shop, how far are we responsible?
Imagine a customer slipping and getting hurt, or a shop sign falling onto someone else's property. Cases like these can bring medical bills and compensation that the business owner is legally liable to pay.
Third-party liability insurance can help carry the cost of claims for incidents that are covered, so it is another area that shops, restaurants, cafés and offices that receive visitors should look at.
If you already have shop insurance, open the policy and check whether it includes third-party liability, and what the limit is.
Once you have employees, how do you plan for illness and accidents?
Besides the building and the stock, the people who work for you are a key part of keeping the business going.
Group personal accident insurance or group health insurance is an employee benefit that helps ease treatment costs under the plan you choose. Owners can start with a budget they can manage, then consider cover that suits the nature of the work and the size of the team.
Can the premium be claimed as a business expense?
For a company or a registered partnership, premiums that relate to the business, are actually paid, are supported by evidence and meet the legal conditions can be counted as a tax-deductible expense.
Shop owners who file personal income tax need to look at the type of income and the method of deducting expenses. In particular, if you use the flat-rate deduction, you cannot deduct the business's insurance premiums on top of the flat-rate amount.
It is clearer to talk this over with your accountant beforehand, including the name of the insured, the payment documents and how the expense is recorded so that it matches your business.
How much budget do you need to start business insurance?
Some plans start at a few hundred baht a year, but you need to look at what type of business it is, what sum insured you choose and what cover you get.
Take a look at the sample plans on Prakanthai.com and click through to read the details of each one.
| Insurance plan | Starting premium per year | Who are these starting prices for? |
|---|---|---|
| BKI fire insurance for shops and business premises | THB 699 | Offices and clinics, sum insured THB 500,000, flood not included |
| BKI fire insurance for shops, flood included | THB 861 | Offices and clinics, sum insured THB 500,000; flood has a limit and an excess under the conditions |
| Chubb SME Select / Select+ package | THB 997.24 | Select plan, group 1 such as offices or dormitories, sum insured THB 500,000 |
Prices are taken from the product pages, checked on 17 November 2026. The actual premium depends on the type of business, location, building characteristics, sum insured, the plan chosen and the insurer's underwriting decision.
If the budget is limited, what should you cover first?
Start with these three questions
- What damage would stop the business from working?
- If you had to stop for a month, could you still pay salaries, rent and creditors?
- If you had to pay a large sum in damages to a customer, would your reserves be enough?
The answers help you choose cover that fits the problem more closely. After that, compare prices, limits and the part you pay yourself, putting the incidents that would hit the business hardest first.
Not sure yet? Start by telling us about your business
Just tell us what business you run, which province it is in, roughly how much property you have and what worries you most. If you already have a policy, send it over and we can look at whether the cover still suits your business today.
Prakanthai.com has non-life insurance advisers, and an accountant is available for additional advice on the accounting and tax questions that apply case by case. Our team helps explain the conditions, compare plans and guide you through the steps, coordinating with the insurer when something happens.
Want to know which plan your business should start with? Message us and let's talk it through.
LINE Official: Click to chat with our team — @prakanthai
Phone: +66 2 459 2223
Email: [email protected]
About Prakanthai.com and how to contact our office
Non-life insurance broker, licence no. 5104000004
Cover and claim payments follow each insurer's conditions. Keep a reserve for the excess, and for damage that goes over the limit or falls outside the cover.