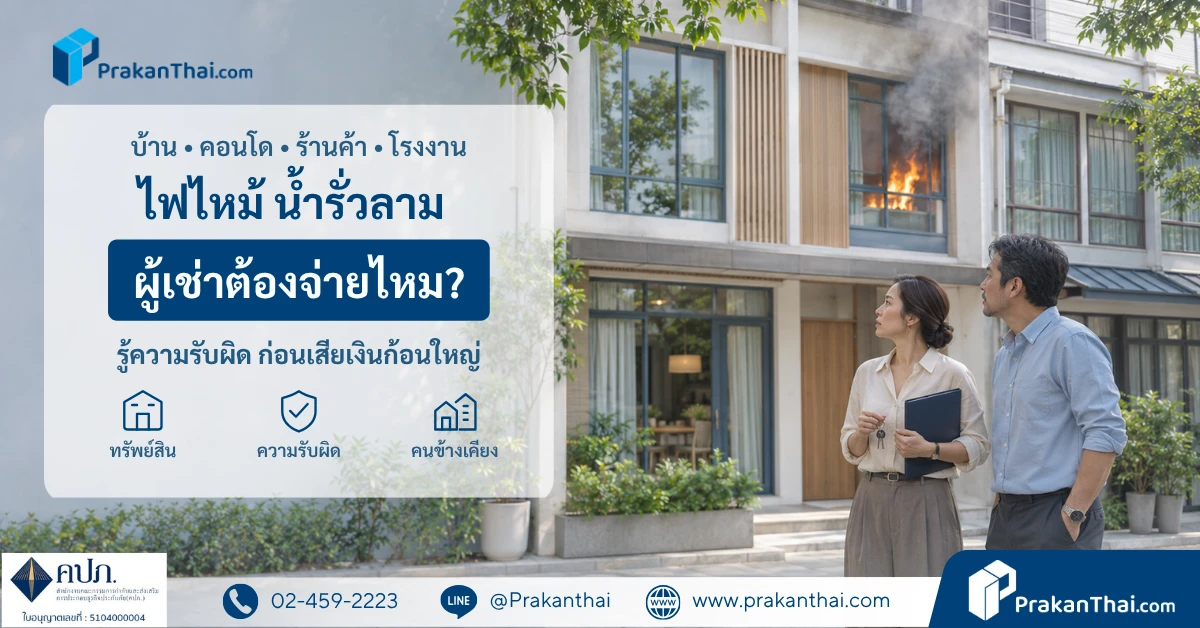
The house or building isn't ours, but the damage can become our debt
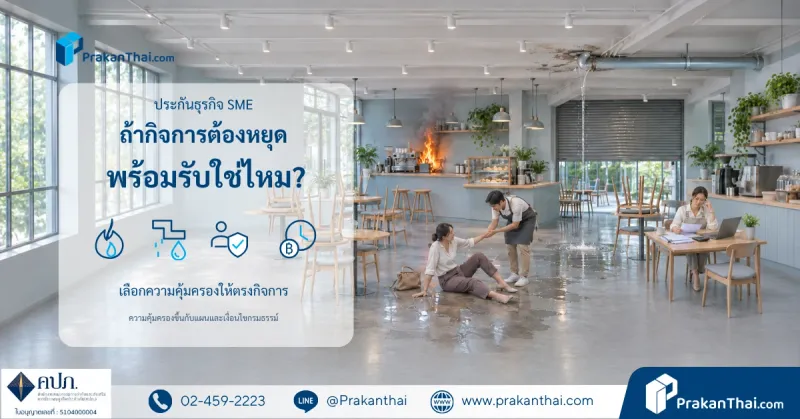
People who rent a house, condo, shop, office, warehouse or factory usually think about the rent and the deposit before moving in. But if a fire spreads to the house next door, water leaks into the unit below, or a customer slips in the shop, who is responsible for the damage?
A tenant may have to pay if they are liable under the law or under a contract term that is enforceable. It depends on the cause, who had the duty of care and the supporting evidence, not just on where the incident happened.
Everyday situations that could leave a tenant paying a large sum
| Incident | Damage that may follow |
|---|---|
| Leaving the stove on, or overloading a power strip until it catches fire | The rented house, furniture and neighbouring houses are damaged |
| A washing machine hose comes loose, or a tap is left running and water flows into the unit below | Ceilings, walls, floors and the property in other units are damaged |
| Welding or a production process in a factory throws off sparks | The rented building, stock, machinery and surrounding property are damaged |
| Leaving a shop floor wet without dealing with it or putting up a warning, so that a customer slips | The business may be asked to pay medical costs and damages if it is liable |
The law makes a tenant liable for damage to the rented property caused by their own fault, by people living with them or by a sub-tenant. Damage that spreads to other people may also be liability in tort.
But if a shared pipe bursts, or the building's original systems are faulty, you need to check who has the duty to maintain them. A tenant does not have to pay in every case. However, when you find a defect or danger, tell the owner or the juristic person straight away and keep evidence, because leaving it until it causes more damage may make the tenant liable. drr.go.th
A deposit is not a ceiling on liability
Say you have paid a deposit of THB 40,000 but cause damage that you are liable for amounting to THB 2 million. That does not mean paying only the deposit ends the matter. What you must pay depends on your liability and the damage that can be proved.
Another common misunderstanding is “the owner has home insurance, so we won't have to pay.” If the insurer has paid the owner or the neighbour, it may take over their rights (subrogation) and claim against a tenant who is liable. So check the conditions that relate to tenants too. drr.go.th
Tenant insurance: look at all 4 parts
Insurance can help ease the financial damage, but it has to match the property, how it is used and the liability you want covered.
1. The tenant's own property
For example furniture, appliances, office equipment, stock, raw materials or machinery. Choose fire insurance, property insurance or business insurance as appropriate. The cover depends on the items of property and the perils insured; not every cause of machinery breakdown can be claimed.
2. Liability for the rented house or building
Check whether it covers the tenant's liability for the building and the owner's property, and for which causes, because some kinds of third-party liability insurance exclude property in your possession or care, so a suitable extension is needed. thailandgi-ktaxa.cdn.prismic.io
3. Third-party liability
For example a fire spreading to the house next door, a water leak damaging another unit, or a customer injured by something the tenant or business is legally liable for. Check the scope, limit, excess and exclusions against the real risk.
4. Business interruption, for tenants of business premises
Once the fire is out, a shop or factory may still not be able to reopen while some costs carry on. Business interruption insurance may help compensate for lost profit and costs under the conditions. Generally it has to be linked to damage to property from a covered peril; it does not pay every time the business stops. MSIG Insurance
Points to ask about clearly: “water damage” cover for property does not confirm that liability is covered when water leaks into another unit, and a fire extension for a rented building does not always mean water damage is included.
If the lease makes you liable for more than your duties under the law, check whether the insurance covers that liability too.
Tenants of shops, warehouses and factories should state the type of business, production process, storage of goods and use of flammable substances truthfully, so that the insurer can consider a suitable plan.
See property insurance options for businesses and SMEs
Before signing the lease or choosing insurance, check these 4 things
- Liability clauses: who repairs what, and in which cases the tenant is liable, especially wording that makes you liable for every cause even when you are not at fault.
- Condition of the premises: take photos before handover, check the electrics, water and equipment, and report defects in writing.
- Existing insurance: ask which parts the owner or the juristic person has covered, and whether the tenant is covered too.
- Limits and exclusions: look at your own property, the rented building and damage that could spread to other people, including liability you take on in the contract.
If something happens, put safety first, tell the owner or the juristic person and the insurer as soon as possible, keep photos and evidence, and have the cause checked before agreeing on the amount of compensation.
Questions tenants often ask
I'm not the owner of the house or building. Can I still buy insurance?
Yes, subject to the insurer's conditions, for example property insurance where the tenant has an insurable interest, and suitable liability insurance. You must state your status as a tenant correctly. You do not have to own the building to start planning your cover. www.axa.co.th
If water leaks into the unit below, am I always liable?
Not always. You need to check the cause, who had the duty of care and what each party did. For example, leaving a tap running and a burst shared pipe are different sets of facts.
The factory owner already insures the building. What else should the tenant check?
Check machinery, stock, raw materials and the business's own property, plus liability for the rented building, third parties and business interruption, because the owner's building insurance does not confirm that every part of the tenant's needs is covered.
Not sure where to start with your risks?
Send us “insurance for tenants” along with the type of premises and how you use it, and the Prakanthai.com team will help work out which cover you should have and explain the conditions before you decide.
We have an office and a team you can reach, and we can help coordinate with the insurer when something happens, depending on the facts and the policy conditions.
- LINE Official: @prakanthai — click to talk to our team
- Phone: +66 2 459 2223
- Email: [email protected]
Underwriting and claim payments depend on the facts, the limits, the conditions and the exclusions of each policy.