Loss-of-use compensation vs V-Motor Add On: who pays your travel costs while your car is being repaired?
- Published: 24 August 2026
- Category: Insurance guides
Loss-of-use compensation vs V-Motor Add On: who pays your travel costs while your car is being repaired?
Car in for repair for 7 days: who pays for the taxis? The minimum THB 500 a day that drivers who are not at fault often never claim
Your car is hit on Monday morning, and in the afternoon the garage tells you, “We're waiting for parts, about 5–7 days.”
The repair cost is covered by insurance, so that's not the worry. The worry is how you'll get to work and pick up the kids for these 7 days. A return taxi trip costs THB 300–400 a day, and over seven days that comes to more than THB 2,000.
The question is: do you always have to pay this yourself?
The answer is not always, and many Thais are already entitled to this money without ever having claimed it.
The short answer
There are 2 ways to help with travel costs while your car is being repaired.
The first option costs you nothing extra: it is loss-of-use compensation, which you can claim from the other party's insurer when you are not at fault. There are minimum rates under the rules of the OIC (Office of Insurance Commission): for private cars with up to 7 seats, at least THB 500 per day.
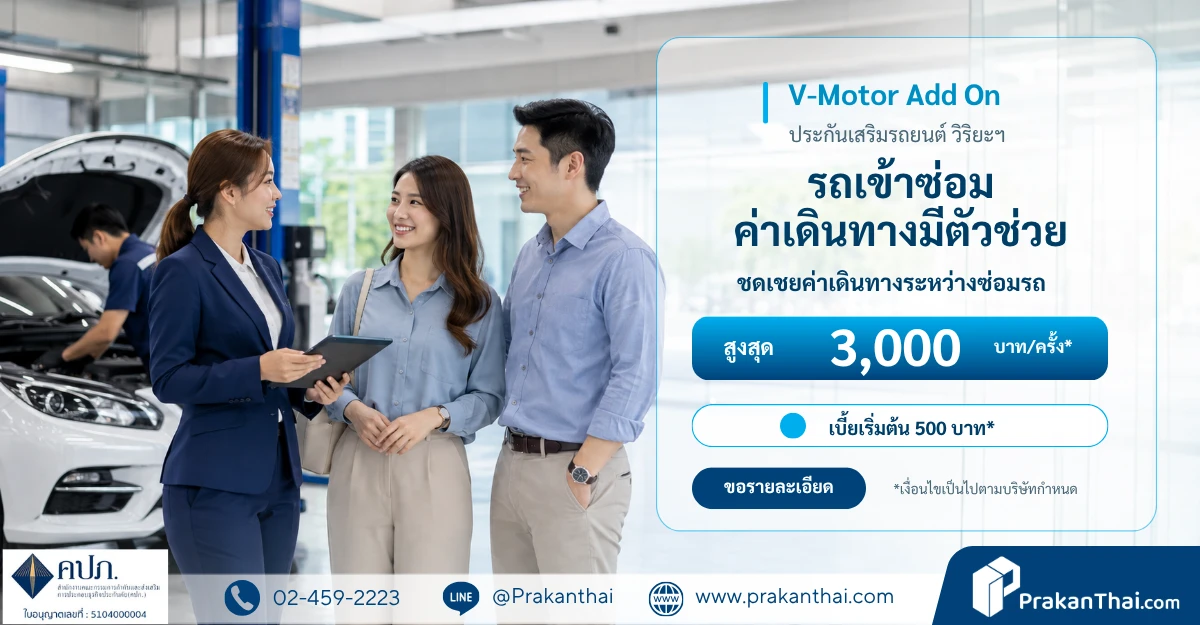
The second option has to be bought: the V-Motor Add On cover from Viriyah Insurance. The premium is THB 500–750 per year, and it pays travel compensation of THB 2,000–3,000 per incident when the car collides with a land vehicle and the repair takes more than 12 hours.
The key point is that these two don't replace each other; each fills a different gap. Read on for another 3 minutes and you'll know which group you're in.
Compare them at a glance in 30 seconds
| Loss-of-use compensation | V-Motor Add On | |
|---|---|---|
| Do you pay extra? | No, it is a legal right | Yes, you buy it: premium THB 500 or 750 per year |
| Who pays you | The other party's insurer | The insurer under the policy |
| Main condition | You must not be at fault, and the other party must be identified | The car collides with a land vehicle, and the repair takes more than 12 hours |
| How much | At least THB 500 per day, for the actual number of days under repair | THB 2,000 or 3,000 per incident, up to 5 times per year |
| Weak spot | If you are at fault or the other party can't be found, you can't claim | Hitting a post or a wall, flood and fire don't qualify |
Now you can see why we say they don't replace each other. The first can't be used when you're at fault, and the second can't be used when you hit something that isn't a vehicle.
Option 1: loss-of-use compensation, a free right most people never claim
If you are not at fault, the law sees being without your car during the repair as a form of damage the other party must be responsible for, not something you have to put up with yourself.
Minimum rates under the OIC rules
| Vehicle type | Minimum per day |
|---|---|
| Private car, up to 7 seats | THB 500 |
| Public hire car, up to 7 seats | THB 700 |
| Vehicle with more than 7 seats | THB 1,000 |
The word “minimum” is very important. It means that if you have evidence of higher actual costs, such as car hire receipts or ride-hailing bills, you can claim more than the minimum rate. You are not limited to exactly THB 500.
Put it in numbers: your car is in for repair for 7 days and you are not at fault, so the minimum rate alone comes to THB 3,500. That is money many people leave unclaimed because they don't know they can ask for it.
How to claim
- First, confirm clearly that the investigation finds you not at fault.
- Prepare a copy of the policy, the claim form, the repair intake slip and the date you got the car back, a copy of the vehicle registration book and your ID card.
- Send a letter of claim to the other party's insurer, stating the number of days you were without the car and the amount you are claiming.
- Attach evidence of actual costs, if you have any, to ask for more than the minimum rate.
- Keep proof of every submission. If there is no response for an unreasonable time, chase it in writing, then consult the OIC hotline 1186.
A limitation you have to accept: if you are at fault, or it is an accident with no other party, such as reversing into the wall of your own house, this right doesn't apply at all, and this is the gap that Option 2 fills.
Option 2: V-Motor Add On, an extra purchase of under THB 1,000 a year
Viriyah Insurance's V-Motor Add On is not car insurance and does not pay repair costs in place of your main policy. It is personal accident insurance that comes with travel compensation while your car is in for repair.
Two plans, with just one difference
| Plan 1 | Plan 2 | |
|---|---|---|
| Annual premium | THB 500 | THB 750 |
| Travel compensation | THB 2,000 per claim | THB 3,000 per accident |
| Maximum number of claims | 5 claims per policy year | 5 claims per policy year |
| Accident cover: death, loss of limbs, loss of sight or total permanent disability | THB 50,000 per person | THB 50,000 per person |
A difference of THB 250 a year in exchange for THB 1,000 more compensation per incident. If you use your car every day and have no spare car, this difference hardly needs thinking about.
When it pays. Every condition must be met: the insured car has an accident, it is a collision with a land vehicle, the car goes in for repair because of that incident, and the repair takes more than 12 hours. You can claim up to 5 times per policy year.
When it doesn't pay: read this carefully before you decide. Many incidents people commonly claim for don't qualify, including reversing into a car park pillar, scraping a wall, hitting a gate, breakdowns from wear and tear, engine failure, flood and fire, because none of them is a collision with a land vehicle.
The part many people overlook: the accident limit of THB 50,000 per person covers both the driver and passengers without naming them, and by the nature of personal accident insurance, this limit is paid on top of the rights you already have under both compulsory motor insurance (CMI) and the endorsements in your main policy, not deducted from them.
Three questions to ask before you buy, because underwriting conditions can change at any time
- What are the 12 hours counted from: the actual repair time or the time the car is at the garage, and does it include time waiting for parts?
- If your main insurance is with another insurer, can you still buy this?
- Can you buy it mid-year, or do you have to buy it at renewal?
These three questions can completely change whether it is worth it. Message our team and we'll check the latest rules for you.
So what should you do?
If you use your car every day and have no spare car, do both: know your right to loss-of-use compensation for when you're not at fault, and consider the Add On to cover you when you are at fault, because the day you're at fault is the day nobody pays your travel costs.
If your family has only one car, this matters even more, because one car in the garage means the whole household has to find new ways to get around.
If you have several cars, work from home, or already have a replacement car benefit, frankly this Add On may not be necessary; knowing your right to loss-of-use compensation is enough. We don't recommend buying something you won't use.
After an incident, do these 5 things straight away
- File a claim with your main insurer first and get the incident notification number.
- Ask clearly who is at fault, because that decides whether you can claim loss-of-use compensation.
- Note the date the car goes into the garage and the date you get it back, and ask the garage for a document confirming them. This is the starting evidence for both options.
- Keep your travel receipts for that period, both taxi fares and car hire, which you can use to claim more than the minimum rate.
- If you have the Add On, ask for your entitlement to be checked as well. Don't wait for someone to tell you, because the system doesn't remind you automatically.
Frequently asked questions
Do you have to be not at fault to claim loss-of-use compensation? Yes. It is a claim for damages from the party who is liable, so you claim from the other party's insurer when you are not at fault. If you are at fault or there is no other party, this right doesn't apply.
Is it only THB 500 a day? THB 500 is the minimum rate for private cars with up to 7 seats. If you have evidence of higher actual costs, you can claim more than the minimum rate.
Does V-Motor Add On pay for car repairs too? No. It is personal accident insurance that provides travel compensation and accident cover. Repair costs remain the job of your main car insurance policy, under that policy's conditions.
If you reverse into a pillar in a car park, do you get compensation? It doesn't qualify, because a pillar is not a land vehicle. The product information states that it must be a collision with a land vehicle.
Can you claim if the car is in the garage for just one day? For the Add On, the repair must take more than 12 hours; taking the car in for an inspection or a minor repair and collecting it again doesn't qualify. Loss-of-use compensation is calculated on the actual number of days you were without the car.
If you claim loss-of-use compensation, can you still receive compensation from the Add On? They are separate contracts with different payers, so in principle they are assessed separately, but always confirm the conditions with the insurer for your actual case first.
Not sure what you're entitled to? Let us check for you
Many people spend upwards of THB 1,000 on taxis while their car is being repaired, even though they are entitled to claim it back, because nobody told them.
Message us on LINE with just 2 things: the number of seats shown in the registration book and your main insurer and expiry date. We'll reply telling you which right you should use and, if you want to buy extra cover, which plan suits how you use your car. Free of charge, with no hard sell.
LINE Official: @prakanthai Tel. +66 2 459 2223 Website: www.prakanthai.com
Prakanthai.com, non-life insurance broker, serving since 2004, broker licence no. 5104000004
Note: This article provides general information and is not part of any insurance contract. The loss-of-use compensation rates are the minimum rates under the rules of the OIC. The product information, premiums and underwriting conditions of V-Motor Add On are based on information published by Viriyah Insurance Public Company Limited, which may change. Underwriting and claim payment decisions are a matter for the insurer under the terms, conditions and exclusions of the policy. Readers should check the actual policy schedule before deciding.