Information checked as of 14 November 2026 | by Prakanthai.com
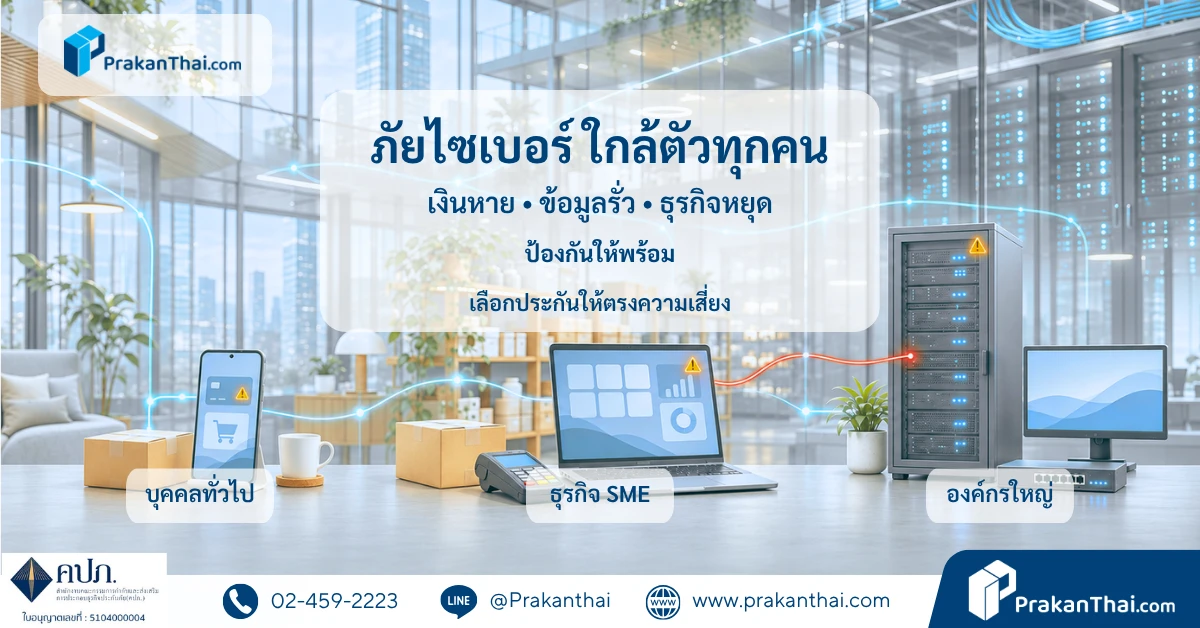
Money stolen from an account, goods paid for online that never arrive, a shop unable to sell because its system is locked, or large organisations going down at the same time — damage from the digital world can hit both everyday life and business.
There is insurance designed for the risks of individuals, SMEs and large organisations, but the types of cover and the conditions differ. So start by knowing what you stand to lose, then choose insurance that matches it [5][6][7]
News from around the world reflects risks that people in Thailand should be ready for
- Binance: The company disclosed on 30 October 2026 that digital assets worth about USD 6.3 billion had been withdrawn without authorisation [1]
- Cooling systems in Europe: Switzerland's cyber agency warned on 10 November 2026 that intruders could change temperatures and settings remotely, risking damage to food, medicines and other temperature-controlled goods [2]
- Microsoft 365: An outage on 12–14 November 2026 affected email and related services; the company said it was a technical problem, not a cyberattack [3]
- US aviation: On 13 November 2026, US time, the FAA temporarily stopped aircraft departures nationwide because of a communications problem; officials said they had found no evidence of a cyberattack [4]
These incidents have different causes. The shared lesson is that the more we depend on digital systems, the more damage from an attack or an outage can reach us. Note that losses from the incidents above are not automatically covered by cyber insurance.
1. Individuals: your spending money and online income may disappear
If you use Mobile Banking, shop online or sell online, the risks close to home include
- Being tricked into entering your details on a fake website, after which criminals use them to steal money from your account
- Paying for goods and being cheated, with nothing delivered
- Sending goods to a buyer, then finding it was a fake purchase, so you are never paid
The impact is that money set aside for spending is lost, side income is disrupted, and time is spent contacting the bank or gathering evidence.
The relevant cover is personal cyber insurance (Personal Cyber Insurance). Some plans cover theft of money through data theft or phishing, as well as fraud in online buying and selling, depending on the sections chosen. For example, Bangkok Insurance covers buying goods that are never received, and some plans cover selling goods and not being paid, with the period, limit and conditions set out clearly [5]
Money stolen from your account and a decision to transfer money to a scammer may be assessed differently, so do not assume that every kind of online scam will be refunded by insurance
Read more: Personal cyber insurance
2. SMEs: lost sales, customer data and the cost of fixing systems
The risk is not limited to online shops. Many kinds of business can be affected in different ways, for example
- Shops and online shops: the sales system or back office is locked, so you cannot take orders, check stock or ship goods
- Clinics, schools and accounting offices: data on customers, students or clients leaks, so the incident has to be investigated and demands dealt with
- Restaurants, hotels and cold-storage businesses: equipment control systems are accessed, which may disrupt service or damage goods
- Factories and transport businesses: production-planning or delivery systems stop, causing delays and extra costs
Business cyber insurance (Business Cyber Insurance) may help with the cost of investigating an incident, restoring data, losses from business interruption and liability for data leaks, depending on the cover bought and the policy conditions [6]
A question SMEs should ask before buying is “If an outside provider's system goes down, are we covered?”, because a shop can stop selling even when its own systems have not been attacked
As for spoiled goods or damaged equipment caused by a cyber incident, the related property cover must be checked separately. General cyber insurance does not mean all physical damage will be paid.
3. Large organisations: one incident can affect customers and partners in many countries
Banks, hospitals, airlines, digital platforms and multinational businesses have many interlinked systems and data. If an incident happens, it may affect services at many branches, production, payments or large amounts of customer data, along with IT, legal and crisis-communication costs.
There is cyber insurance for large organisations whose cover can be adjusted to the risk, such as liability for data leaks, legal defence costs, specialist incident-response fees, and extra cover for extortion or network interruption, although some sections must be bought as add-ons [7]
Organisations doing business in several countries should therefore check subsidiaries, outside service providers, territorial scope and limits against how they actually operate, as well as industry-specific exclusions. Theft of digital assets is not automatically covered under every cyber policy.
Prevent first, and prepare help for when damage happens
All three groups can start reducing risk from the same principles, then tighten up according to the scale of use [8][9]
- Protect your accounts: use separate passwords, turn on multi-factor authentication, and never disclose passwords or OTPs
- Change how you verify money: confirm the money has actually arrived before you ship goods, and if a business partner announces a change of account, call to confirm using a number you have already verified
- Look after data and devices: update systems, back up data separately from the main system, test restoring it, and limit access rights
- Prepare a response plan: have a backup way of working, keep evidence when something happens, and know how to contact the bank, the IT team, the provider or the insurer
Before choosing insurance, check in full what events are covered, who the insured is, what the limit is, and what excess (deductible) or waiting period applies, and whether the damage you are worried about needs extra cover to be bought
Choose cyber insurance that fits your life and your business
Prakanthai.com is ready to help explain the conditions and coordinate the insurance side, so you understand which plan suits personal use, a shop or your organisation
Message us on LINE Official and type “cyber insurance consultation”, say whether you are an individual, a business owner or an organisation and what risk you are worried about, and our team will check the plan options and underwriting conditions with you before you decide.
- LINE Official: @prakanthai — click to talk to our team
- Phone: [+66 2 459 2223 (line 24592223)](tel:024592223)
- Email: [email protected]
Cover depends on the terms, exclusions, limits and policy conditions. The insurer decides on underwriting and claims.
References
- Binance: Security Incident Institutional Update #2 — 30 October 2026 and FBI: information confirming the Binance attack — 31 October 2026
- Switzerland's national cyber agency: Cooling and refrigeration control systems — 10 November 2026
- Reuters: Microsoft restores service to Outlook and Teams after global outage — incident of 12–14 November 2026
- Reuters: US to resume flights after air traffic network failure sparks chaos — incident of 13 November 2026, US time and FAA statement
- Bangkok Insurance: frequently asked questions on personal cyber insurance and product details and the online buying and selling section
- Chubb Thailand: cyber insurance for business
- AIG Thailand: Cyber Insurance — CyberEdge
- FTC: Cybersecurity for Small Business
- NIST: Cybersecurity Basics
The examples of impact on each group describe risks that may arise; they do not confirm that the Thai organisations given as business types have already suffered these incidents. The examples of cover refer to real products, but do not confirm that every plan of every insurer has the same conditions, or that every applicant will pass underwriting.