Premium data as of 10 November 2026 · compiled by Prakanthai.com
A coffee machine bought three years ago is damaged by fire from an electrical short circuit. The owner files a claim and is asked: "Does the policy pay new-for-old, or with depreciation deducted?"
The answer decides whether the shop gets enough to buy a new machine or has to find tens of thousands of baht more out of its own pocket. So how do the two differ?
What is Replacement Value?
Short answer: Replacement Value means the claim is paid at the price needed to buy or repair the property new, in equivalent condition, with no deduction for depreciation from age or use. This differs from Actual Cash Value, which deducts depreciation first. Shop insurance that pays on a Replacement Value basis and has no excess, such as Chubb SME Select / Select+, pays closer to the new price, subject to the sum insured and the sub-limit for each category.
New-for-old vs depreciation deducted: how much do they differ?
| Topic | Replacement Value | Depreciation deducted (ACV) |
|---|---|---|
| Based on | The price of an equivalent new item | The new price minus depreciation for age |
| The older the item | The payout stays the same | The payout gets smaller |
| Money the shop has to add itself | Less | More |
A worked example to illustrate
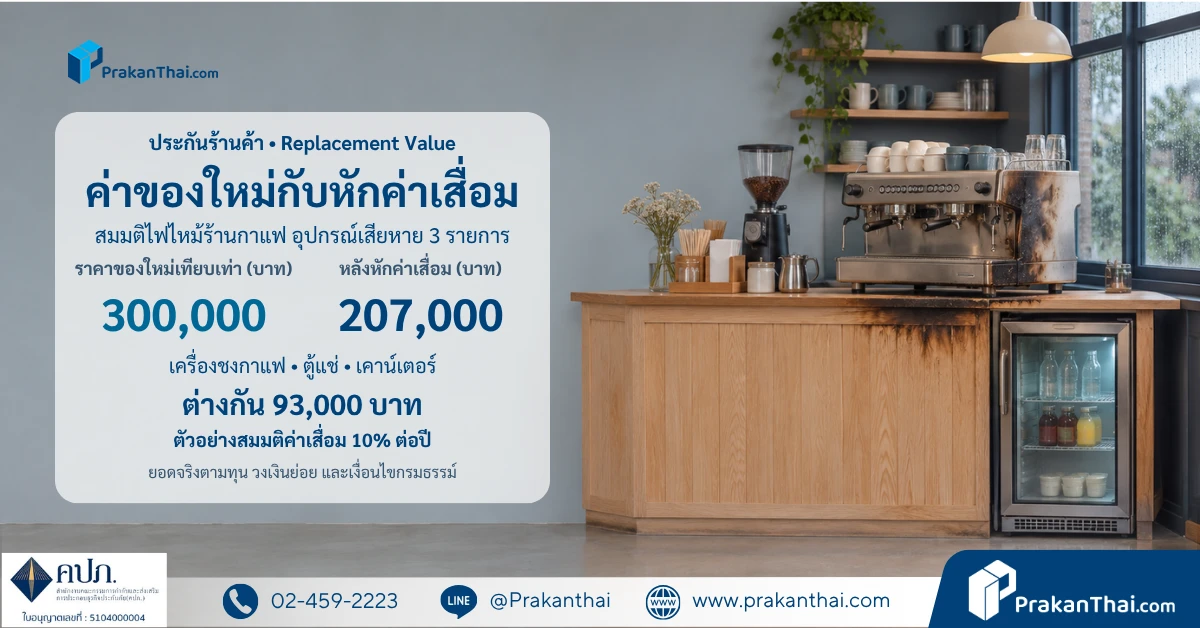
Suppose a fire hits a coffee shop and damages three items, with depreciation assumed at 10% per year
| Item | New price (THB) | With depreciation deducted (THB) |
|---|---|---|
| Coffee machine, 3 years old | 150,000 | 105,000 (30% deducted) |
| Chiller cabinet, 5 years old | 60,000 | 30,000 (50% deducted) |
| Counter, 2 years old | 90,000 | 72,000 (20% deducted) |
| Total | 300,000 | 207,000 |
- Paid on a Replacement Value basis: about THB 300,000
- Paid with depreciation deducted: about THB 207,000. The shop has to add another THB 93,000 itself to buy the same set again.
- If the plan has an excess, the payout is reduced further by the stated amount.
The depreciation figures are assumptions for illustration. The amount actually paid depends on the insurer's claim assessment. The rule of thumb: the more years the shop's equipment has been in use, the more a new-for-old payout gives you compared with a depreciation-deducted one.
What does having no excess add?
The excess (deductible) is the first amount the insured has to pay themselves each time they claim. If the plan has none, even small claims such as broken glass or stolen items are paid according to the damage the insurer assesses, with no first amount taken off. For the basics, read Excess vs Deductible: what is the difference?
What limits remain even when claims are paid new-for-old?
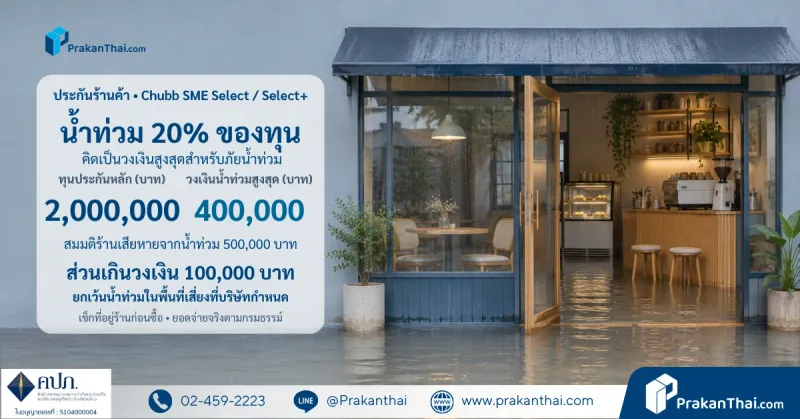
- The sum insured and the sub-limits still apply. For example, Chubb SME Select / Select+ pays no more than THB 50,000 / 100,000 for damage to electrical equipment and no more than 20% of the sum insured for flood.
- Some types of property are not insured at all, such as mobile phones, laptops, tablets, cameras and other portable electronic devices.
- If the sum insured is much lower than the real value, you may not receive the full damage. So set the sum insured close to the new price of all the property in the shop.
- The detailed conditions follow the policy. Chubb SME Select / Select+ uses the conditions of the standard safe-business insurance policy.
Which shop insurance pays new-for-old and has no excess?
Chubb SME Select / Select+ from Chubb Samaggi Insurance pays on a Replacement Value basis with no excess in any case. It covers fire and natural perils at the full sum insured and accepts coffee shops, restaurants, clinics, dormitories, hotels, retail shops and offices. The total premium starts at THB 997.24 per year (data as at 10 Nov 2026). The actual premium depends on the business group, the sum insured and the plan. See the full details at Chubb SME Select / Select+ shop insurance.
If your business is not in a group this plan accepts, try comparing BKI fire insurance for shops and business premises, from THB 699 per year.
Send us the type of business, the shop address and the approximate value of your equipment and stock. Our team will help set the sum insured and send the premium back within the business day. LINE Official: @prakanthai · Tel. +66 2 459 2223
Frequently asked questions
Do all shop insurance plans pay new-for-old?
Not every plan does. Check the product document or the policy to see which basis of payment is stated and which types of property it applies to.
Should the sum insured be based on the purchase price or today's new price?
For plans that pay on a Replacement Value basis, base it on what you would have to pay to buy or repair the item new today, because that is the basis used to calculate the claim.
Does new-for-old make the premium more expensive?
Each plan's premium is calculated from several factors together: the cover, the excess, the business group and the sum insured. Compare from quotes with the same sum insured.
Notes
The product information in this article is based on the SME Select / Select+ product document, edition 01/2025, and the sales document for the product from Chubb Samaggi Insurance Public Company Limited, checked on 10 November 2026. The item prices and depreciation rates in the examples are assumptions for illustration. It is general information and not part of the insurance contract. Premiums and conditions may change as the insurer announces. Underwriting and claim payments are decided by the insurer. Prakanthai.com is a non-life insurance broker, not an insurer, licence no. 5104000004. Please read the policy and the quote in full before deciding.