Is SME shop insurance necessary? | Prakanthai.com
- Published: 3 October 2026
Is SME shop insurance necessary? | Prakanthai.com
Is SME shop insurance necessary?
4 problems that could hit your investment
How much have you invested in your shop, and how much have you set aside to get it back on its feet after something unexpected?
Building up a shop takes savings, time and hard work, but a fire or flood can damage your equipment and stock, and force you to stop selling while the shop is repaired.
The working capital you set aside for buying stock, paying staff or expanding the business may then have to go on restoring the shop instead.
SME shop insurance helps cover damage from the perils and to the property named in the policy, so business owners should choose cover based on the problems their shop could face and the limits they really need www.oic.or.th
1. A single fire may mean buying new equipment and stock all at once
Picture a coffee shop whose coffee machine, fridges, counter and ingredients are damaged, or a shop where a fire destroys the stock along with the shop fittings. Many of the costs of reopening may come at the same time.
Why insurance matters: it helps cover damage to insured property from fire and the other perils the policy covers
For SME Select+, the insured property includes business premises (excluding foundations), furniture, machinery, office equipment and stock, so list the items and sums insured to suit your shop www.chubb.com
2. A flood damages stock and equipment, and the money for the next round of stock may not be enough
Shops that keep stock, fridges or equipment on the ground floor should assess which property could be damaged if water gets in, and how much it would cost to reopen.
Why insurance matters: if the plan includes flood cover, it helps cover the damage within the set limits and conditions
Prakanthai.com's SME Select / Select+ page states a flood limit of 20% of the sum insured. For example, if the plan you choose sets this proportion and the sum insured is THB 1,000,000, the flood limit works out at THB 200,000 www.prakanthai.com
This figure is the limit of cover; the actual payout depends on the damage and the policy conditions. Also check whether the limit is enough and whether it applies per event or per year.
3. The shop closes for repairs and income stops, but some costs still have to be paid
After an incident, the shop may have to stop selling while the premises are repaired or equipment is replaced, while rent and some regular expenses may keep running.
Why you should check for additional cover: some plans pay a daily compensation when property damaged by a covered peril leaves the business unable to operate and it has to close temporarily www.chubb.com
Before you buy, check whether this section is included, how much it pays per day, for how long, and which conditions apply, so you can weigh it against your shop's reserves.
4. A customer has an accident, and the business may be liable for the damage
If a customer is injured or their property is damaged in an incident for which the business is legally liable, the shop owner may face further claims for damages.
Why you should check your cover: the third-party liability section may help cover that liability when the incident falls within the scope and conditions of the policy www.chubb.com
Businesses with regular walk-in customers should check this section, along with its limits and exclusions, before deciding.
Is SME Select / Select+ right for your shop?
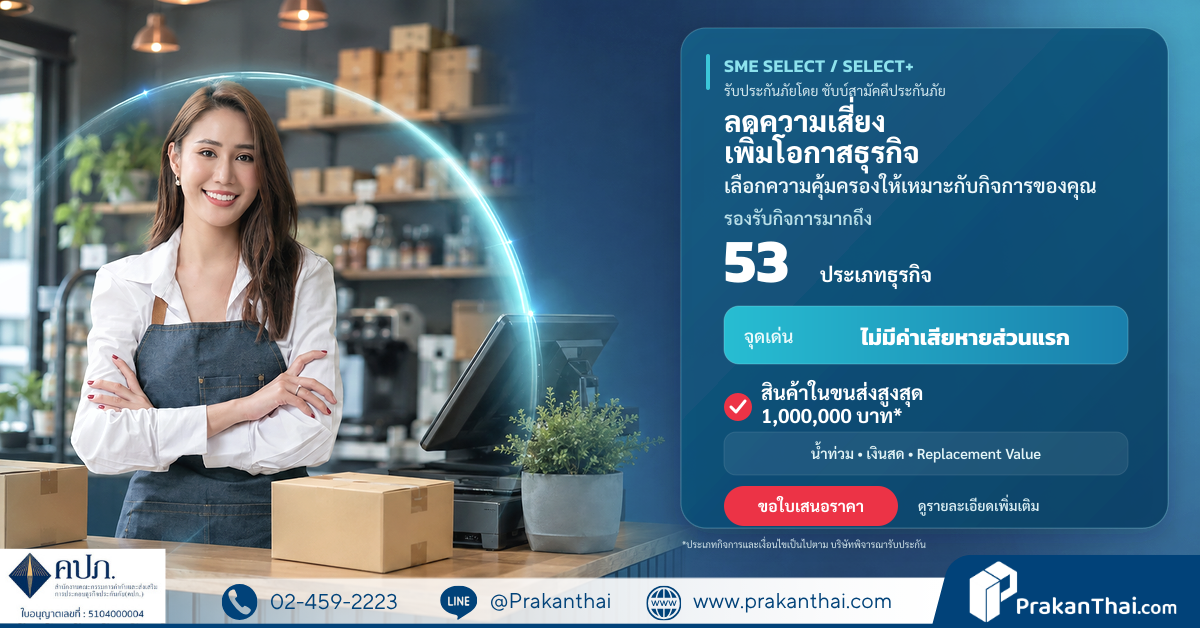
SME Select / Select+, offered through Prakanthai.com, is an option for small and medium-sized businesses. SME Select+ from Chubb Samaggi Insurance Public Company Limited has property cover sections and additional cover such as burglary, cash and third-party liability www.prakanthai.com
The cover in each section must be checked against the plan you choose, and you should state your type of business, location and list of property accurately, matching how they are actually used
Renting your shop? What should you check?
Check who the insured is and which policies list your stock and equipment. If the building owner already has insurance, ask to see its scope of cover before considering extra cover for your business.
Can you choose on the premium alone?
Compare the premium together with the sum insured, flood limit, covered property, excess (deductible) and exclusions, so the plan you buy covers your shop's key risks the way you need it to.
Check your cover now, before you have to fund your shop's recovery yourself
You have already invested a lot in your shop. Checking your insurance today shows you which risks to prepare for and what limits to choose.
Message Prakanthai.com on LINE, type “Check shop insurance” along with your type of business and the province where you are located, and our team will check your business type, explain the key cover and prepare an offer based on your shop's details.
- LINE Official: @prakanthai
- Phone: [+66 2 459 2223 (line 24592223)](tel:024592223)
- See the SME Select / Select+ details www.prakanthai.com
Underwriting, cover, limits and claim payments are subject to the plan and the policy conditions. Buyers should study the details before deciding.
Price: - | Start date: 2 October 2026 |
End date: 31 December 2027 |