Viriyah EV 2+ insurance (dealer repair) from THB 13,000 | Prakanthai
- Published: 10 October 2026
Viriyah EV 2+ insurance (dealer repair) from THB 13,000 | Prakanthai
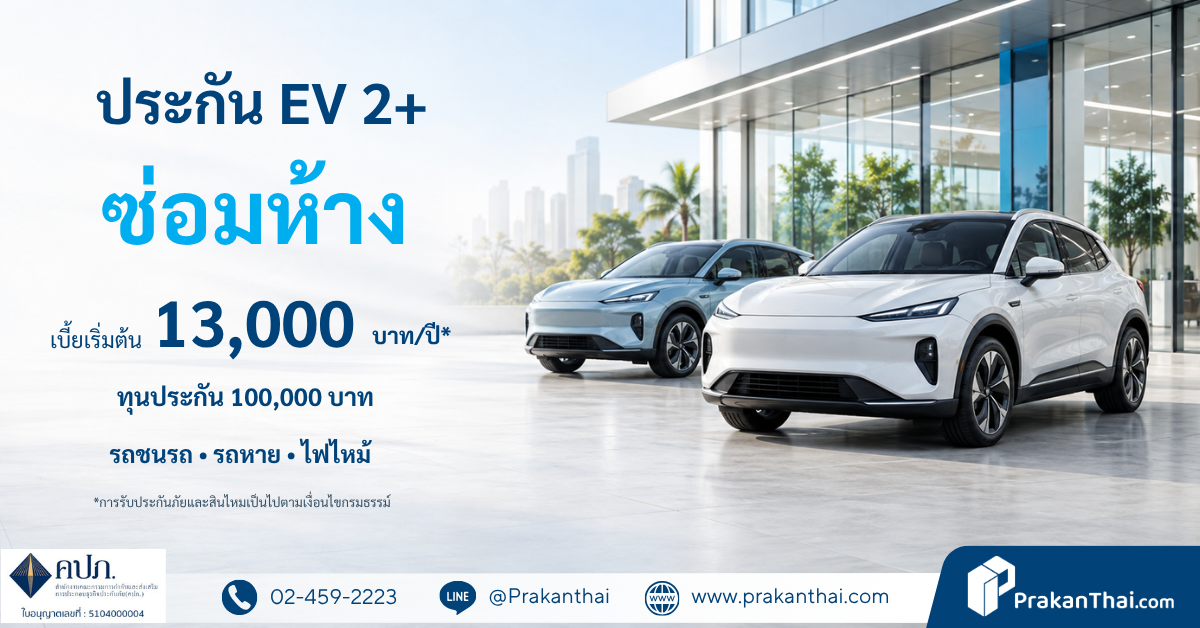
Viriyah EV 2+ insurance with dealer repair, for electric vehicle (EV) owners who want a lower premium than Class 1, from THB 13,000 per year
Premium data as at 5 September 2026
Underwritten by Viriyah Insurance Public Company Limited · Premiums from THB 13,000–17,000 per year, depending on the sum insured chosen · Highlight: dealer repair is still available, subject to the insurer's conditions
Renewing your EV insurance for the second or third year, but the Class 1 premium is over your budget? Dropping to Class 3 worries you, because if you really do crash you would have to pay for all the repairs yourself. Which should you choose?
Viriyah's EV 2+ insurance sits in the middle: it covers the car itself only for certain incidents, in exchange for a premium you can keep under control, and still offers dealer repair, but there are conditions you should check carefully first.
Viriyah EV 2+ insurance: who is it for, and how much is the premium?
Viriyah EV 2+ dealer-repair insurance suits electric vehicle owners who mainly drive in the city and want a lower premium than Class 1. It covers the car in a collision with a land vehicle, fire and theft, up to the sum insured you choose (THB 100,000–500,000), plus third-party liability. Premiums from THB 13,000 per year (sum insured THB 100,000, data as at 5 Sep 2026). The actual premium depends on the car model, the car's age, how it is used and the sum insured you choose.
What does Viriyah EV 2+ insurance cover?
Coverage Limit Conditions to check Damage to the car from a collision with a land vehicle Up to the sum insured chosen, THB 100,000–500,000 Hitting a post, wall or other object is not covered Fire / theft Up to the sum insured chosen As defined in the policy Battery Within the sum insured chosen Only damage from a covered collision or fire; deterioration not included Third-party bodily injury or death THB 500,000 per person – Third-party property THB 1,000,000 per accident – Personal accident (driver + 5 passengers) THB 50,000 per person – Medical expenses (driver + 5 passengers) THB 50,000 per person – Driver bail bond THB 500,000 per accident – Flood Not stated in the reference table If you need it, ask for a quote that states it clearly
| Coverage | Limit | Conditions to check |
|---|---|---|
| Damage to the car from a collision with a land vehicle | Up to the sum insured chosen, THB 100,000–500,000 | Hitting a post, wall or other object is not covered |
| Fire / theft | Up to the sum insured chosen | As defined in the policy |
| Battery | Within the sum insured chosen | Only damage from a covered collision or fire; deterioration not included |
| Third-party bodily injury or death | THB 500,000 per person | – |
| Third-party property | THB 1,000,000 per accident | – |
| Personal accident (driver + 5 passengers) | THB 50,000 per person | – |
| Medical expenses (driver + 5 passengers) | THB 50,000 per person | – |
| Driver bail bond | THB 500,000 per accident | – |
| Flood | Not stated in the reference table | If you need it, ask for a quote that states it clearly |
Roughly how much is the Viriyah EV 2+ premium?
Reference annual premiums by sum insured, data as at 5 September 2026
| Vehicle sum insured | Starting premium per year |
|---|---|
| THB 100,000 | From THB 13,000 |
| THB 200,000 | From THB 14,000 |
| THB 300,000 | From THB 15,000 |
| THB 400,000 | From THB 16,000 |
| THB 500,000 | From THB 17,000 |
The actual premium depends on the car model, the car's age, how it is used, the sum insured chosen, and whether you choose cover with or without an excess (deductible). This table has not been confirmed to include tax and duty or compulsory motor insurance (CMI). The amount you actually pay is the one in the written quote.
A worked example to illustrate
Is a higher sum insured worth it? A simple rule: each extra THB 100,000 of sum insured adds THB 1,000 to the starting premium. For example, raising the sum insured from THB 200,000 to THB 400,000 raises the starting premium from THB 14,000 to THB 16,000, so you pay an extra THB 2,000 per year for a repair limit that is THB 200,000 higher.
What if you hit a post? If you reverse into a post in a car park and damage the bumper and sensors, the car itself is not covered under this plan.
Who is Viriyah EV 2+ insurance for?
- EV owners whose Class 1 renewal premium is over budget but who still want dealer repair
- People who mainly drive on roads with other traffic, where the main risk is colliding with another vehicle
- People who park in spacious or attended car parks, where the risk of hitting a post or wall is low
- People who want fire and theft cover, which standard Class 3 does not have
Who should not buy this plan yet?
- Cars whose finance contract requires Class 1: check your contract first. If it requires Class 1, you cannot use a 2+ plan instead. See Class 1 EV insurance with dealer repair for new cars (red plates)
- People who often park or drive in flood-prone areas: the reference table does not state any flood cover
- People who drive in narrow lanes or park in buildings with many pillars: if you hit an object with no other vehicle involved, the car itself is not covered
- People who expect insurance to cover battery degradation: this plan does not cover deterioration, reduced capacity or normal wear and tear
- Cars where a single serious crash could cost more than THB 500,000 to repair: the plan's maximum sum insured may not be enough, so compare it with Class 1, where the sum insured is based on the car's value
What limitations should you check before deciding?
- The car itself is covered only for collisions with a land vehicle, as defined in the policy
- The sum insured is not the price of the car: the insurer pays up to the sum insured you chose, and the insured pays any repair costs above it
- Battery cover is conditional: only damage from a covered collision or fire is covered, and it shares the car's sum insured with no separate limit
- Excess (deductible): options are available with or without an excess; without one, the premium is slightly higher
- Dealer repair is subject to the insurer's service centre conditions: check before buying that your car's make and model qualify
- Charging cable and wall charger: not stated in the reference information, so check against the actual policy
Want to know the actual premium for your car? What do you need to send?
Send just 2 things
- A photo of the registration book's front page
- The front page of your current policy
Our team will send a written quote back within the business day, showing the premium incl. tax and duty, the excess (deductible), and compulsory motor insurance (CMI) if you want it at the same time. We will tell you straight which plan is good value, and explain any differences in conditions before you pay.
LINE Official: @prakanthai · Tel. +66 2 459 2223
Frequently asked questions
Can my EV model get this plan?
It depends on Viriyah Insurance's assessment, which looks at the make, model, year and how the car is used. You can send us your car details to check first.
Does the starting premium of THB 13,000 include tax and compulsory motor insurance (CMI)?
The starting premium of THB 13,000 per year is a reference premium for a sum insured of THB 100,000, data as at 5 Sep 2026. It has not been confirmed to include tax and duty or CMI. The final amount is the one in the quote, before you pay.
Can I get compulsory motor insurance (CMI) at the same time?
Yes. Mention it when you ask for a quote and the total will be on a single quote. If you want to check first that the cover dates match your vehicle tax cycle, read New CMI rules from 1 September 2026: match your cover dates to your vehicle tax
Can I claim if my charging cable or home wall charger is damaged?
The reference information for this plan does not say, so it must be checked against the actual policy. If this matters to you, mention it when you ask for a quote and our team will check the conditions for you first.
Who approves claims?
Underwriting and claim payments are decided by Viriyah Insurance. Prakanthai.com, as the broker, helps coordinate and follow up for you.
Should you choose EV 2+ or EV Class 1?
If you are worried about hitting objects or flooding, or your car is worth much more than the THB 500,000 sum insured, Class 1 is the better fit. But if your main risk is colliding with other vehicles and you want to keep the premium down, 2+ can help. You can get quotes for both to compare on the same terms, for example MuangThai Motor EV Class 1 electric vehicle insurance with dealer repair
Notes
The coverage and premium information on this page is based on Viriyah Insurance Public Company Limited's product information as at 5 September 2026. It is general information and not part of the insurance contract. Premiums and conditions may change as announced by the insurer. Underwriting and claim payments are decided by the insurer. Prakanthai.com is a non-life insurance broker, not an insurer, broker licence no. 5104000004, providing services since 2004. Please read the policy and the quote in full before deciding.
Price: THB 13,000 | Start date: 5 September 2026 |
End date: 31 May 2027 |
Buy online
Fill in the car, registered owner and keeper details and the Prakanthai team will call you back to arrange the policy.